Home › Blog › Daily Market Review
Daily Market Review · US close
SPX stays long gamma through the Fed; Thursday's expiry now prices the Alphabet test
SPX rose 0.3% to 7,744, 40 points above its gamma flip, and net GEX held at +$18.7B. VIX slipped to 16.9, but VIX1D rose to 13.2 and Thursday's SPX expiry carries 15.1% ATM vol after Alphabet fell about 9% after hours. Here are the levels for Thursday.
- The Fed held at 3.75–4% in a 10–2 vote, with two dissents for a hike. SPX rose 0.3% to 7,744 and NDX 0.5%. After hours, Microsoft rose about 4% on a beat and Alphabet fell about 9% on an earnings miss.
- SPX closed 40 points above its 7,704 flip and net GEX edged up to +$18.7B. The close is also above the weekly and monthly flips, but both windows are still slightly net short.
- VIX fell 0.61 to 16.91, while VIX1D rose to 13.15 as Thursday's GDP/PCE and the megacap reactions entered its window. The Oct 29–30 expiries price 15.1–15.2% ATM vol vs 11.4–11.9% for Nov 2–3.
Scoreboard
| Close | Chg | Prev | |
|---|---|---|---|
| SPX | 7,744 | +0.28% | 7,723 |
| NDX | 29,813 | +0.55% | 29,651 |
| VIX | 16.91 | −0.61 | 17.52 |
| VIX1D | 13.15 | +0.62 | 12.53 |
| VVIX | 96.6 | −2.8 | 99.5 |
| VX Nov / Dec | 18.60 / 18.78 | +0.95% M1→M2 | +0.61% |
| VIX / VIX3M | 0.880 | −0.015 | 0.895 |
| 30D ATM IV / skew | 13.2% / 10.5 | −0.5 / −0.5 | 13.7% / 11.0 |
| Window | Net GEX | Chg | Prev | Flip | Call wall | Put wall | |
|---|---|---|---|---|---|---|---|
| SPX | All | +$18.7B | +$0.4B | +$18.3B | 7,704 | 8,000 | 7,000 |
| SPX | Weekly | −$0.4B | +$0.3B | −$0.7B | 7,725 | 7,800 | 7,700 |
| SPX | Monthly | −$8.0B | −$0.6B | −$7.4B | 7,737 | 8,000 | 7,700 |
| NDX | All | +$1.29B | +$0.74B | +$0.55B | 29,424 | 30,000 | 29,000 |
| NDX | Weekly | +$1.01B | +$0.54B | +$0.47B | 29,356 | 30,300 | 29,300 |
| NDX | Monthly | +$1.76B | +$0.60B | +$1.16B | 29,244 | 31,325 | 27,500 |
Dealer gamma by expiry window. All = every listed expiry; Weekly = contracts expiring within 7 calendar days; Monthly = within 30 days. Net GEX in $ per 1% move.
1. The tape: a split Fed, a quiet close, a loud after-hours
The Federal Reserve kept its policy rate at 3.75–4% by a 10–2 vote. Cleveland Fed President Beth Hammack and Governor Lisa Cook dissented in favor of a quarter-point hike. The statement described growth as strong and inflation as still elevated, and Chair Kevin Warsh said one 2027 meeting will be devoted to longer-term strategy with no rate vote. Fed funds futures moved to price roughly an 85% chance of a hike at the Dec. 9 meeting.
Stocks took it calmly. The S&P 500 rose 0.3% to 7,744, the Dow 0.2% to 52,475, the Nasdaq Composite 0.3% to 26,550 and the Russell 2000 0.4%. The Nasdaq-100 did better, up 0.55%, helped by memory chips: US-listed SK hynix shares jumped about 13% after a surge in quarterly profit, and Micron gained about 5%. Oracle rose about 11% after projecting at least $225 billion of fiscal 2030 revenue. Vertiv climbed about 17% on a 61% sales jump and a higher forecast, and Wendy's rose about 14% after confirming a $7.35-a-share proposal from Trian. Enphase and F5 each fell close to 20% on weak outlooks, and Logitech dropped about 12%.
The 10-year Treasury yield rose about 5 basis points to 5.05%, and December WTI crude gained 1.8% to about $101.7. After the bell the megacap picture split. Microsoft rose about 4% in extended trading on a revenue and earnings beat, with cloud revenue of $63.9 billion. Alphabet fell about 9%: revenue of $111.2 billion was in line, but earnings per share of $2.12 missed the $2.99 estimate.
Why it matters for vol: Wednesday's expiry priced 14.5% ATM vol for the Fed, and SPX moved 0.3% close to close, so the FOMC premium went unused. The risk did not disappear; it moved one day forward. Alphabet and Microsoft together are a large share of both indices, and their after-hours moves land in Thursday's expiry together with GDP and PCE.
2. Dealer gamma: long, and a little further from the line
Net GEX across all expiries is +$18.7B per 1% move, barely changed from +$18.3B on Tuesday. The flip is 7,704 (from 7,700), and SPX closed at 7,744, 40 points (0.5%) above it, up from 23 points on Tuesday. Wednesday's expiry rolled off without changing the balance: dealer hedging still leans against moves around the current price.
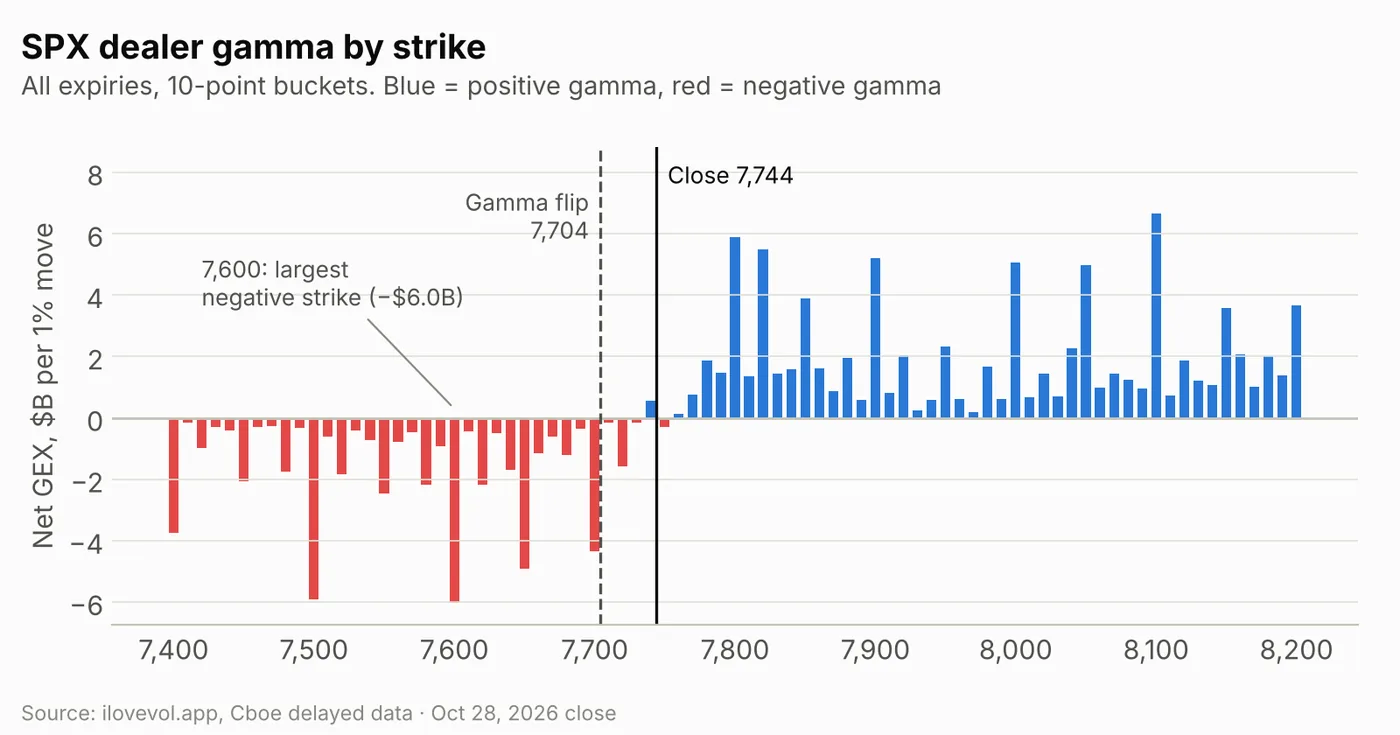
The strike map is the same shape, now with more room above the flip. The first positive bucket over spot is 7,760, and the largest positive strikes are 8,100 (+$6.7B), 7,800 (+$5.9B), 7,820 (+$5.5B) and 7,900 (+$5.2B). Below spot the negative strikes keep their order: 7,600 (−$6.0B), 7,500 (−$5.9B), 7,650 (−$4.9B) and 7,700 (−$4.3B).
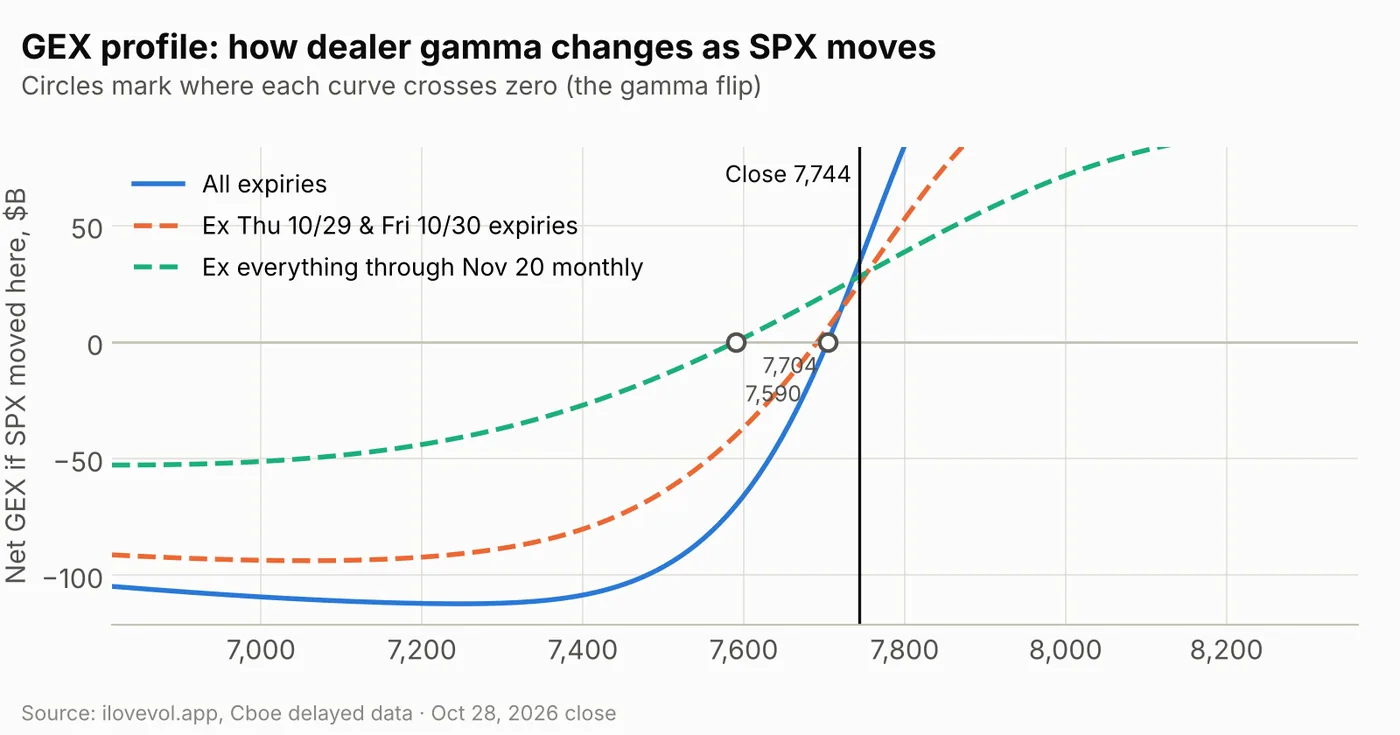
The modeled profile puts all-expiry gamma at today's price near +$34B; the curve is steep here, so small moves change it quickly. Two points:
This week's last two expiries are not the source. Remove Thursday and Friday and gamma at spot is about +$25B, with a flip near 7,691. The long gamma comes from later expiries.
Beyond the November monthly, dealers are long too. Strip out everything through Nov 20 and gamma at spot is about +$28B, with a flip near 7,590. The downside is unchanged: the all-expiry curve still falls to about −$112B near 7,250, so a drop under 7,700 would flip dealers short gamma quickly.
Weekly vs monthly: above every flip, but only just
Splitting gamma by expiry window (net GEX, flip and walls for each window are in the dealer-gamma table under the scoreboard) shows the close sitting above the flip in all three windows for the first time this week, but the near-term windows are still close to flat. Weekly = contracts expiring within 7 calendar days; Monthly = within 30 days.
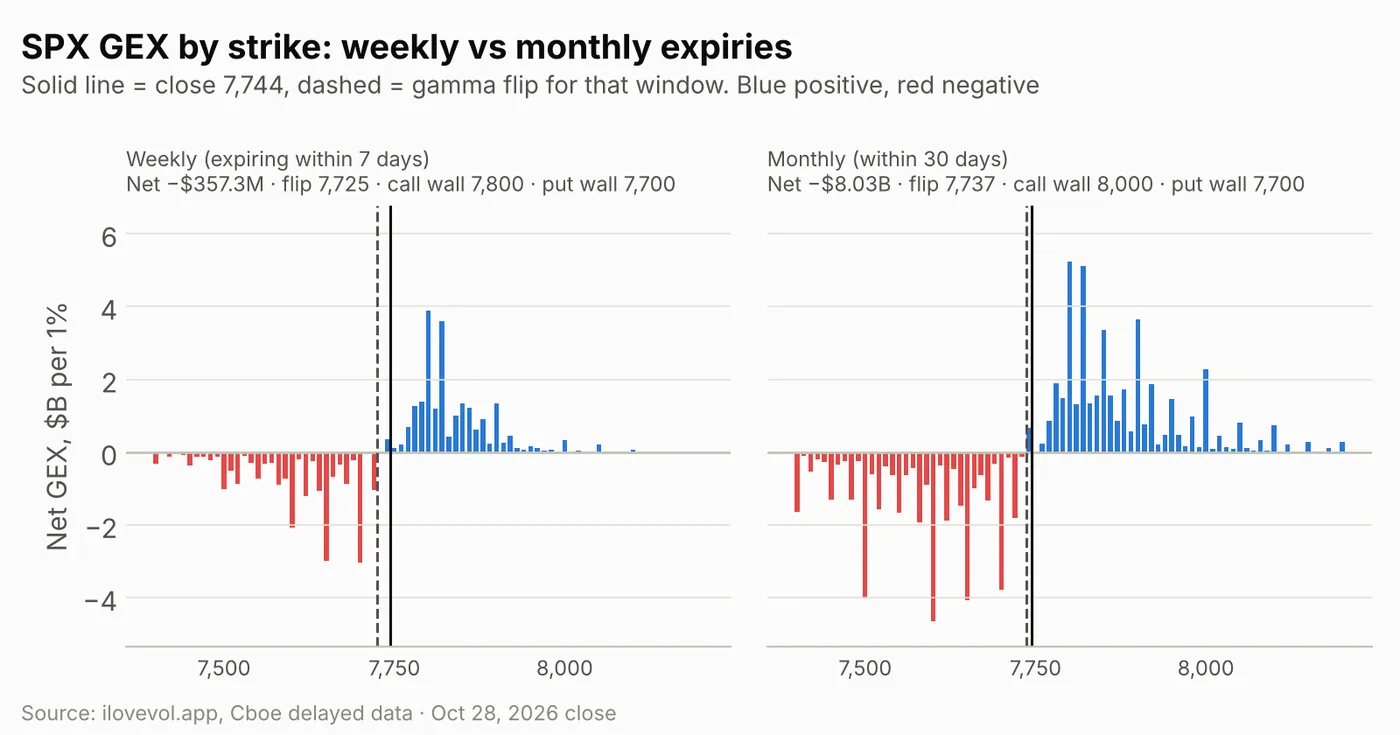
SPX weekly: the next 7 days carry −$0.4B, essentially flat (−$0.7B on Tuesday). The window holds five expiries, Oct 29 to Nov 4, covering GDP/PCE, Amazon, Apple and the midterm vote. Its flip is 7,725, 19 points under the close, with the call wall at 7,800 and the put wall at 7,700. The largest weekly buckets are 7,800 and 7,820 on the call side and 7,700 and 7,650 on the put side.
SPX monthly: the 30-day window is −$8.0B, slightly more negative than Tuesday's −$7.4B. Its flip is 7,737, just 7 points under the close, with the put wall at 7,700 and the call wall at 8,000. Expiries beyond 30 days are net long about $27B, which is what keeps the all-expiry total positive.
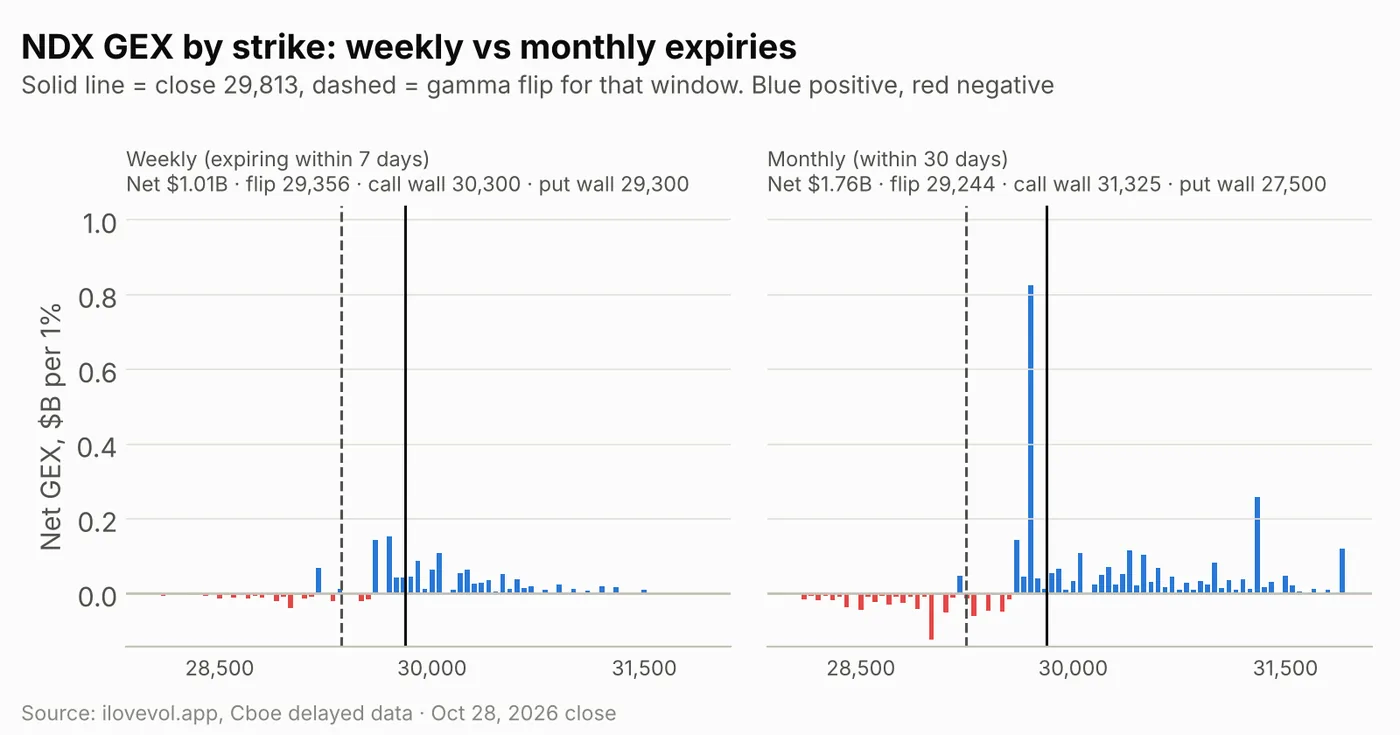
NDX rose 0.55% to 29,813 and its long gamma more than doubled: +$1.29B in total (from +$0.55B), 1.3% above its 29,424 flip. The weekly window is +$1.01B with a flip at 29,356, a 29,300 put wall and a 30,300 call wall. The monthly window is +$1.76B (flip 29,244), and its single largest bucket, 29,700 (+$0.83B), sits just under the close. Expiries beyond 30 days are net short about $0.47B. Alphabet's after-hours drop is the first test of that cushion.
RUT rose 0.4% to 2,831 and turned slightly long gamma (+$0.20B, from −$0.28B). It closed 2 points above its 2,829 flip, between a 2,800 put wall and a 2,850 call wall.
3. The VIX complex: the event moved from Wednesday to Thursday
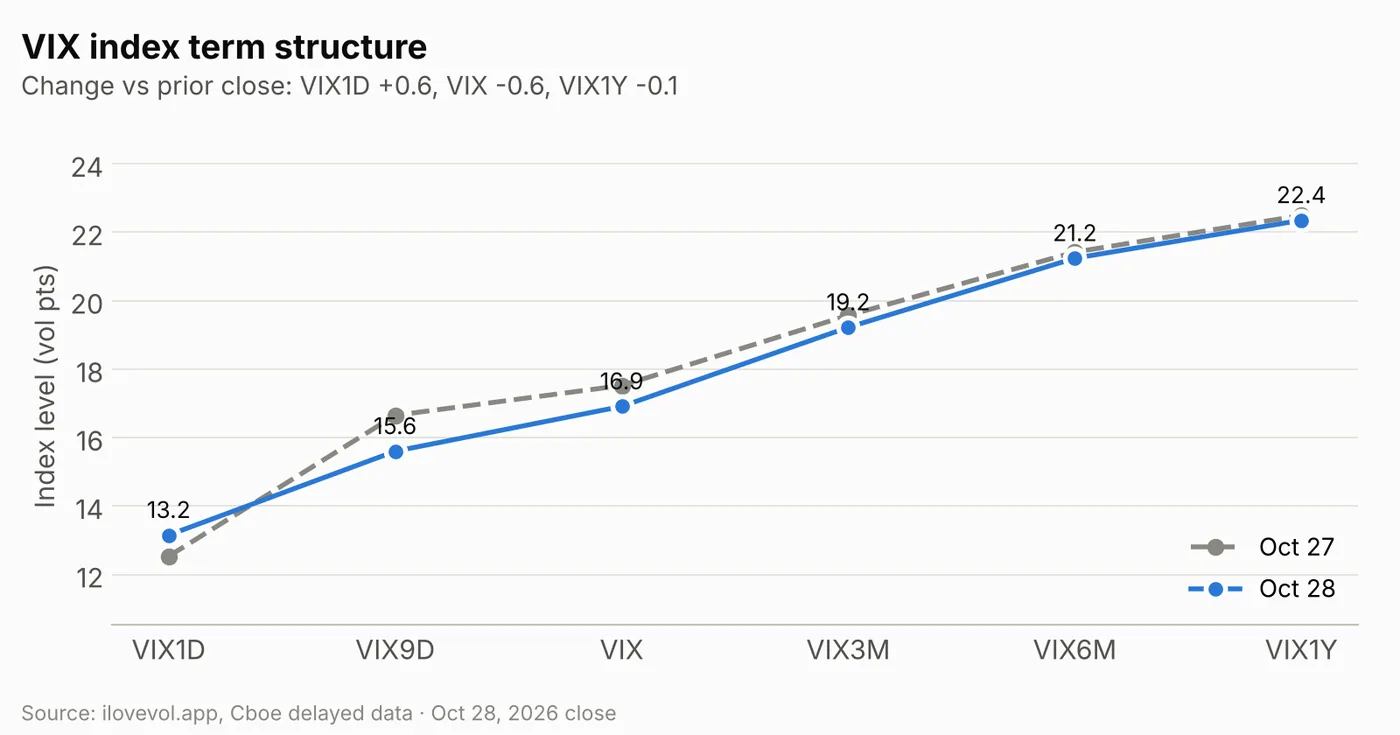
The front and the belly went in opposite directions. VIX1D rose 0.62 to 13.15 as its window rolled from FOMC day to Thursday's GDP/PCE and megacap reactions. VIX9D fell 1.05 to 15.60, VIX lost 0.61 to 16.91, VIX3M 0.35 and VIX1Y only 0.14. The curve is upward sloping from VIX1D to VIX1Y, with no kink.
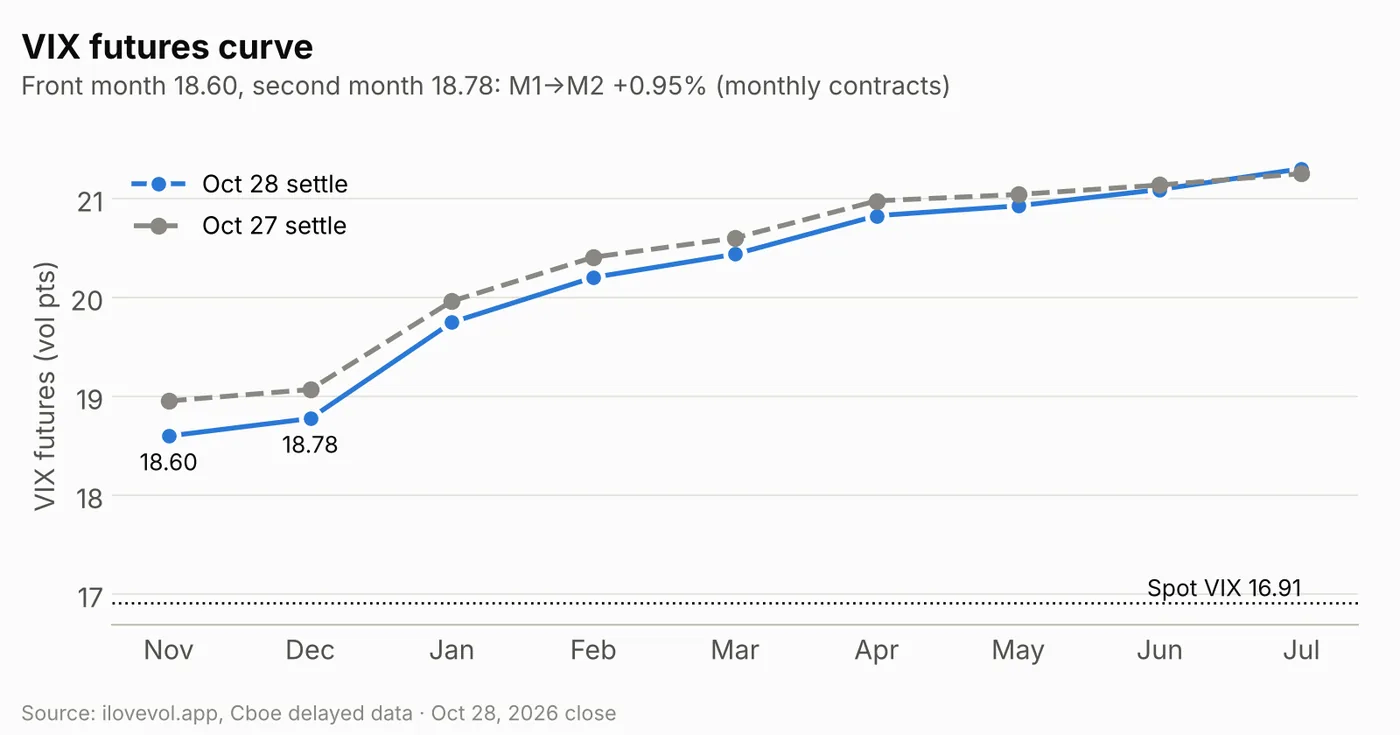
November futures settled at 18.60, down 0.35, and December at 18.78, down 0.29. M1→M2 steepened to +0.95% from +0.61%, so the curve is in contango from the front. Spot fell further than the futures again: November now sits about 10% above spot VIX, up from 8% on Tuesday. VVIX fell 2.8 to 96.6.
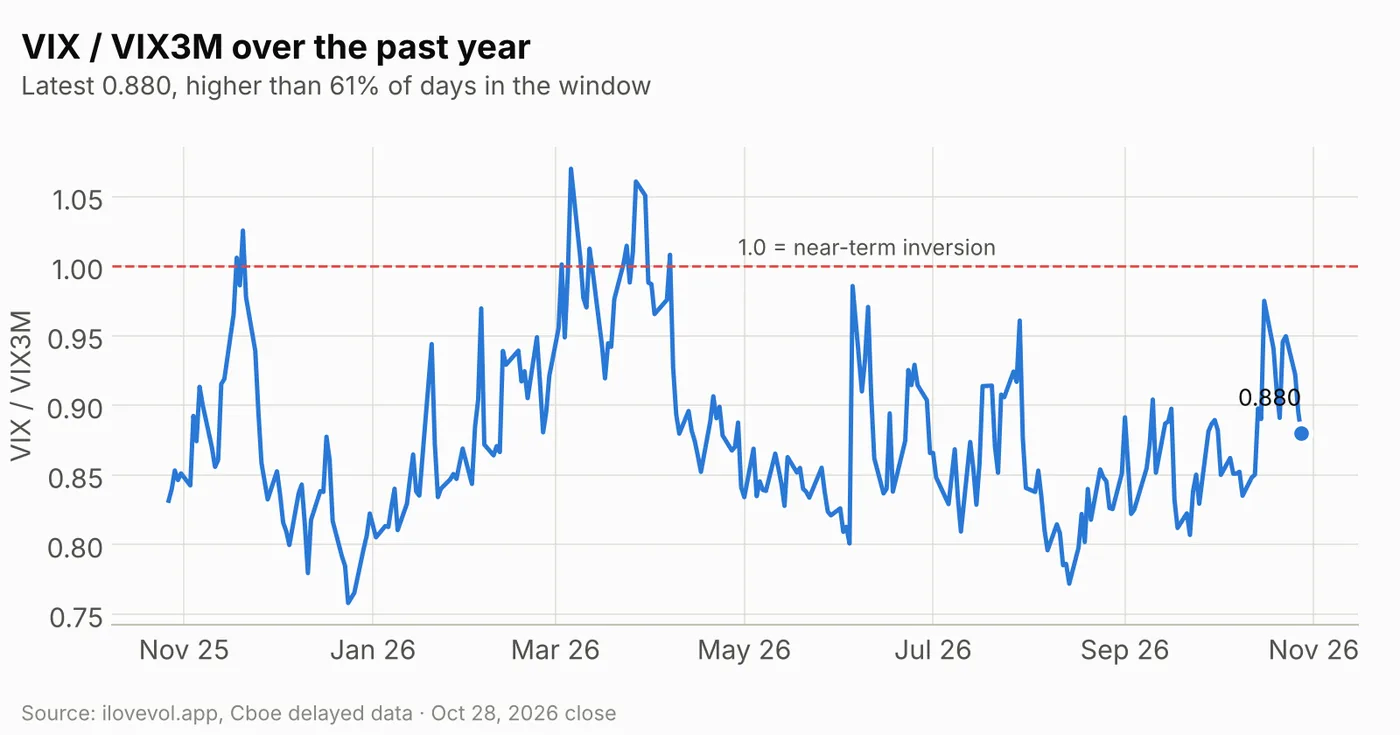
VIX/VIX3M fell to 0.880 from 0.895. That is higher than 61% of the past year's sessions, down from 69% on Tuesday, and well off the 0.97 peak earlier in October. The near end keeps normalizing against three-month vol.
4. Implied vs realized: the premium narrows again
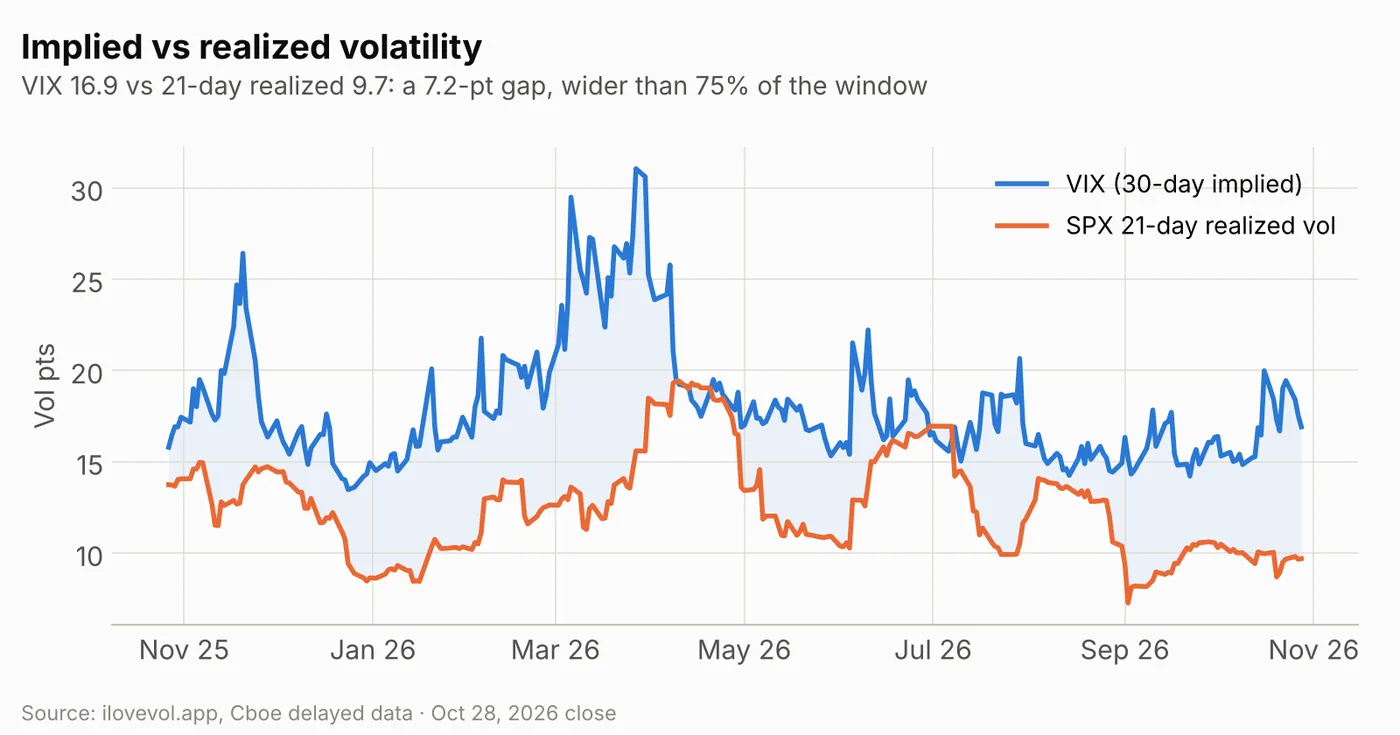
SPX 21-day realized vol is 9.7. With VIX at 16.9, the gap is 7.2 points, down from 7.9 on Tuesday and wider than 75% of the past year (79% on Tuesday). Implied is still about 1.7 times what SPX has delivered. Three quiet up days have shaved the premium a little at a time, while realized has held near 10.
5. The SPX surface: skew eases, Thursday and Friday stand out
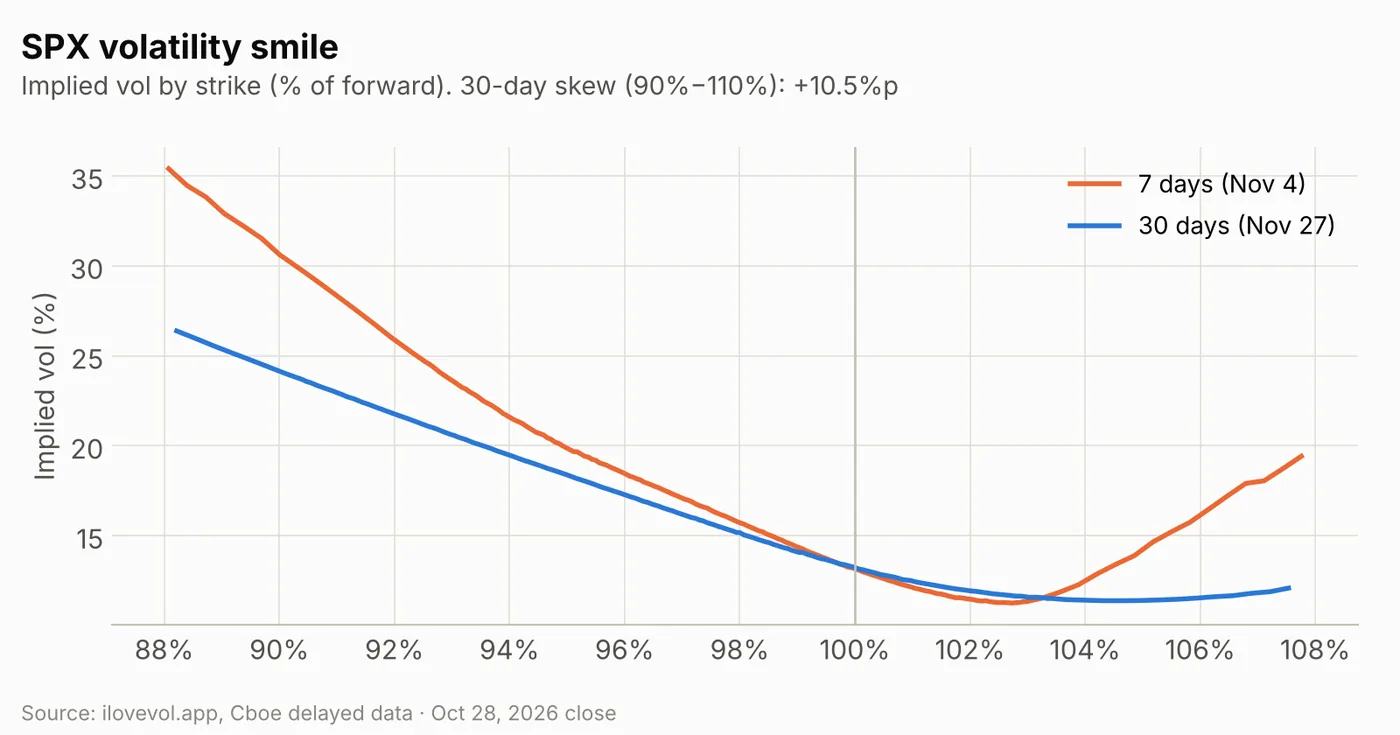
Thirty-day ATM IV fell to 13.2% from 13.7%, and 30-day skew (90% vs 110%) flattened to 10.5 points from 11.0. The 90D−30D term slope steepened to +1.0 point from +0.8. The 7-day smile (Nov 4) is still steep, with 88% puts near 35% vol and the call wing turning up from about 103%. The 30-day curve (Nov 27) is about 26% at 88% and nearly flat on the call side.
The expiry table shows where the event pricing moved. ATM IV is 15.1% for Thursday (GDP and PCE, plus the Microsoft and Alphabet reactions), about a 0.95% or 74-point one-day move, and 15.2% for Friday Oct 30 (after Amazon). It then drops to 11.4% for Nov 2 and 11.9% for Nov 3 (after Apple), rises to 13.1% for Nov 4, the first expiry after the midterm vote, and 13.6% for Nov 6, the day of the October jobs report.
6. Cross-asset Vol Sentiment: calm side of 50, rates still the outlier
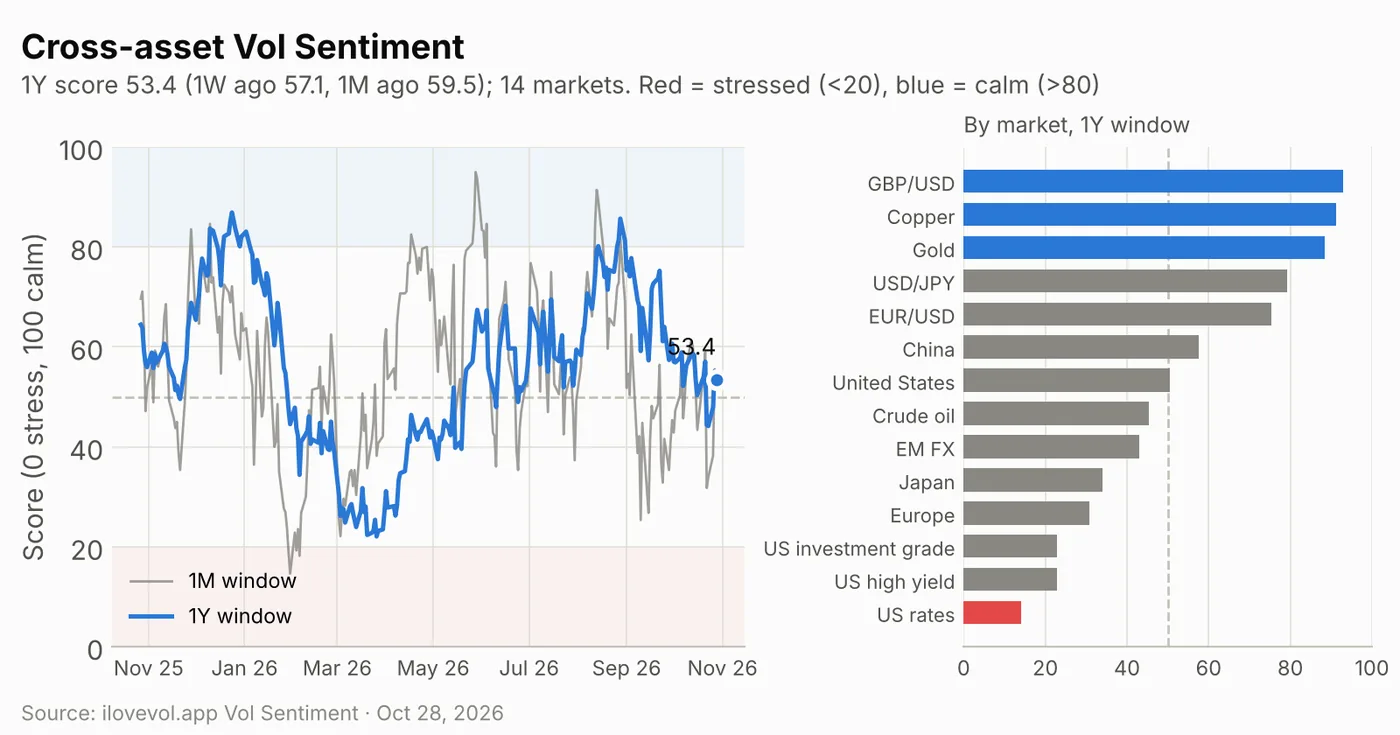
The cross-asset Vol Sentiment score places volatility in 14 equity, currency, rates, credit and commodity markets within its own one-year range (0 = stress, 100 = calm). On the one-year window it is 53.4, just on the calm side of 50, slightly below 55.2 on Tuesday, 57.1 a week ago and 59.5 a month ago. It is higher than 40% of the past year's sessions. The one-month window is 54.5 and the three-month window 38.7.
Only one market is in the stressed zone: US rates (14.2), consistent with a split Fed and a 5% 10-year yield. Investment grade and high yield have eased to 22.9 each, out of the stressed zone. US equities score 50.4, ahead of Europe (30.8) and Japan (34.0). At the calm end are GBP/USD (92.9), copper (91.2) and gold (88.3). Next to the SPX picture, the equity calm now has company in credit, but not in rates. It is context, not a trading signal.
Calendar: the week ahead
Economic data & Fed
| Date | Time (ET) | Event | Note |
|---|---|---|---|
| Thu Oct 29 | 8:30 | Q3 GDP (advance), Sep personal income/spending and PCE inflation, jobless claims | Oct 29 expiry 15.1% ATM vs VIX1D 13.2 |
| Thu Oct 29 | – | ECB decision | |
| Thu Oct 29 | 13:00 | 7-year Treasury note auction ($44B) | 10-year yield at 5.05% |
| Fri Oct 30 | 8:30 | Employment cost index (Q3) | Oct 30 expiry 15.2% ATM |
| Fri Oct 30 | 9:45 | Chicago PMI (Oct) | |
| Mon Nov 2 | 10:00 (expected) | ISM manufacturing (Oct) | Nov 2 expiry 11.4% ATM |
| Tue Nov 3 | 10:00 | JOLTS job openings (Sep) | |
| Wed Nov 4 | 10:00 (expected) | ISM services (Oct) | |
| Fri Nov 6 | 8:30 | October jobs report | Nov 6 expiry 13.6% ATM vs 13.2% Nov 5 |
Earnings
| Date | Timing | Companies | Note |
|---|---|---|---|
| Thu Oct 29 | Before open | Eli Lilly, Caterpillar, Mastercard, Merck | |
| Thu Oct 29 | After close | Amazon, Intel, Starbucks, Strategy | Reaction in the Oct 30 expiry (15.2% ATM) |
| Fri Oct 30 | Before open | Exxon Mobil, Chevron, AbbVie | |
| Mon Nov 2 | After close | Apple | Reaction in the Nov 3 expiry (11.9% ATM) |
| Tue Nov 3 | Before open | Shopify, Eaton, Marathon Petroleum | |
| Tue Nov 3 | After close | AMD, Arista Networks, Amgen, Booking | Reaction in the Nov 4 expiry (13.1% ATM) |
| Wed Nov 4 | Before open | Uber, McDonald's, CVS Health | |
| Wed Nov 4 | After close | Qualcomm, AppLovin, DoorDash |
Volatility dates (expirations, events)
| Date | Event | Note |
|---|---|---|
| Fri Oct 30 | Month-end SPX expiry | Highest ATM IV on the curve (15.2%) |
| Sun Nov 1 | US daylight saving time ends | US data and the open move one hour later in Asia/Europe time |
| Tue Nov 3 | US midterm elections | Nov 4 expiry (first after the vote) 13.1% ATM vs 11.9% Nov 3 |
| Wed Nov 18 | VIX November futures and options expiration | Nov future 18.60, about 10% over spot |
| Fri Nov 20 | SPX November monthly expiration | Removing everything through it leaves gamma at spot about +$28B |
What I'm watching on Thursday
- 7,700–7,704. The all-expiry flip and the weekly and monthly put wall. Above it, dealer hedging dampens moves; a close back below it puts the book short gamma again.
- 7,725–7,737. The weekly and monthly flips, now 7–19 points under the close. Holding above them keeps the near-term windows from adding short gamma.
- 7,800, then 7,600. The weekly call wall and the largest positive strikes above (7,800–7,820), against the largest negative strike below (7,600, −$6.0B) and a profile that falls to about −$112B near 7,250.
- Thursday's 15.1% vs the after-hours split. Alphabet down about 9% and Microsoft up about 4% after the close, with GDP and PCE at 8:30. The expiry implies about a 74-point move; Wednesday's FOMC premium went unused.
- Futures vs spot, and rates vol. November VIX futures sit 10% over spot with VVIX at 96.6. In Vol Sentiment, US rates (14.2) are now the only market in the stressed zone.
Sources
- Yahoo Finance: Nasdaq wavers, S&P 500 and Dow climb as Fed votes to hold rates steady in 10-2 decision
- StockTitan: Stock Market Today Live October 28, 2026: Fed holds rates
- Kiplinger: October Fed meeting, updates and commentary
- eOption: Weekly Event Calendar, Oct 26–30, 2026
- SimianX: Magnificent 7 earnings dates 2026 (Q3 schedule)
- Stockti: Earnings calendar, Nov 2–6, 2026
- FedRateCalc: US economic calendar, November 2026 (BLS release dates)
Volatility data: ilovevol.app. GEX assumes dealers are long calls and short puts. VIX futures use settlement prices. Vol Sentiment: ilovevol.app cross-asset score (0 = stress, 100 = calm), one-year window unless noted.
This review is for informational and educational purposes only and is not investment advice. See the disclaimer.
The Daily Vol sends this review to your inbox each trading day: dealer gamma levels, the VIX curves, the SPX vol surface and the levels to watch. Free, one click to unsubscribe.