Home › Blog › Daily Market Review
Daily Market Review · US close
Tech rout sends SPX 109 points under its gamma flip as GEX hits −$53.9B and VIX futures invert
SPX fell 1.8% to 7,580 and net GEX deepened from −$31.2B to −$53.9B. VIX rose 2.22 to 19.42, the November VIX future now sits above December, and next week's expiries price the midterms and the jobs report well above Monday. Here are the levels for the week ahead.
- Intel (about −29%, worst day since 1974) and Amazon revived AI-spending worries: NDX −3.5%, SPX −1.8% to 7,580. October ended with the Nasdaq down about 5%.
- Net GEX fell from −$31.2B to −$53.9B. SPX closed 109 points under its 7,689 flip and below the weekly (7,725) and monthly (7,736) flips. 7,500 is the largest negative strike (−$8.3B).
- VIX rose 2.22 to 19.42 and VIX1D 5.71 to 19.33. November VIX futures (20.36) now sit above December (19.79). Friday's expiry priced about 74 points and got 140; next Friday's (jobs) carries 16.6% ATM vs 11.7% Monday.
Scoreboard
| Close | Chg | Prev | |
|---|---|---|---|
| SPX | 7,580 | −1.82% | 7,720 |
| NDX | 28,385 | −3.46% | 29,403 |
| VIX | 19.42 | +2.22 | 17.20 |
| VIX1D | 19.33 | +5.71 | 13.62 |
| VVIX | 106.4 | +8.4 | 98.0 |
| VX Nov / Dec | 20.36 / 19.79 | −2.81% M1→M2 | +1.34% |
| VIX / VIX3M | 0.935 | +0.047 | 0.888 |
| 30D ATM IV / skew | 14.9% / 12.9 | +1.7 / +1.3 | 13.2% / 11.6 |
| Window | Net GEX | Chg | Prev | Flip | Call wall | Put wall | |
|---|---|---|---|---|---|---|---|
| SPX | All | −$53.9B | −$22.7B | −$31.2B | 7,689 | 8,000 | 7,000 |
| SPX | Weekly | −$29.1B | +$1.1B | −$30.2B | 7,725 | 7,700 | 7,520 |
| SPX | Monthly | −$55.6B | −$7.3B | −$48.3B | 7,736 | 7,700 | 7,500 |
| NDX | All | −$2.00B | −$2.34B | +$0.34B | 29,186 | 29,675 | 28,000 |
| NDX | Weekly | −$0.54B | −$1.18B | +$0.64B | 28,920 | 29,600 | 28,000 |
| NDX | Monthly | −$1.04B | −$2.19B | +$1.15B | 28,898 | 29,675 | 27,500 |
Dealer gamma by expiry window. All = every listed expiry; Weekly = contracts expiring within 7 calendar days; Monthly = within 30 days. Net GEX in $ per 1% move.
1. The tape: Intel and Amazon close October with a tech rout
Big Tech earnings turned a shaky week into a broad selloff. Intel lost about 29%, its worst session since 1974, after forecasting lower fourth-quarter sales on a severe PC slump and a factory accident in Israel. Amazon's results came in slightly under estimates; AWS grew 39%, but trailing twelve-month free cash flow was an outflow of about $42 billion. Coming a day after Alphabet's worst drop since its IPO, the reports sharpened the question of when AI capex turns into cash. Reddit fell more than 25% on a softer outlook, and chips took the brunt: AMD was down about 12% and the VanEck semiconductor ETF about 8% in the afternoon.
The S&P 500 fell 1.82% to 7,580, the Dow about 1.1% to near 51,770 and the Nasdaq Composite 2.86% to 25,437, its worst day since June 5. The Nasdaq-100 lost 3.46% and the Russell 2000 1.66% to 2,812. About 70% of US issues declined and the S&P 500 tech sector dropped close to 5%. Drugmakers and energy held up, with Regeneron up around 12% and Exxon and Chevron at record highs after refining-driven beats. For October, the S&P 500 lost about 1.2% and the Nasdaq about 5%, while the Dow gained about 1.5%.
Outside equities, Treasuries rallied: the 10-year yield fell about 6–7 basis points to near 4.92%. Oil rose on Strait of Hormuz tanker attacks and Iran headlines, with WTI near $103. Bitcoin fell toward $77,000 after Binance reported a $6.3 billion hack. The Q3 employment cost index rose 0.8%, in line with forecasts. Fed presidents Musalem and Barkin both talked about the need for higher rates after this week's split hold, and markets price a December hike as the most likely outcome.
Why it matters for vol: Friday's expiry priced 15.3% ATM vol, about a 74-point move, and SPX moved 140 points, close to double. 21-day realized vol jumped to 11.6 from 9.7. VIX traded near 22.75 in the afternoon before settling at 19.42, so some of the intraday premium was sold back into the close.
2. Dealer gamma: short and getting shorter
Net GEX across all expiries fell from −$31.2B to −$53.9B per 1% move. The flip moved down to 7,689 (7,723 on Thursday), but SPX fell faster: it closed 109 points (1.4%) under the flip, compared with 3 points under on Thursday. At this level, dealer hedging adds to moves rather than damping them.
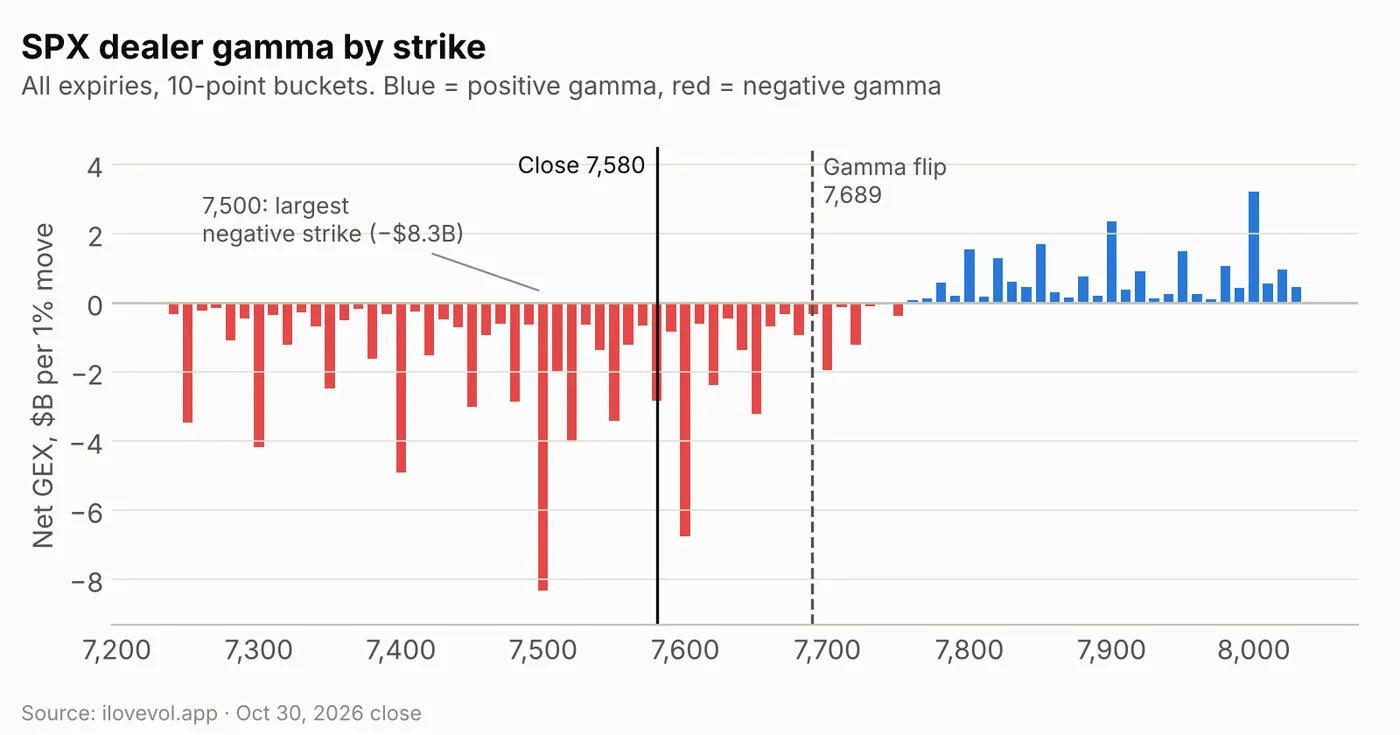
Every bucket from 7,250 up to 7,750 is negative. The biggest are 7,500 (−$8.3B), 7,600 (−$6.8B), 7,400 (−$4.9B), 7,300 (−$4.2B) and 7,520 (−$4.0B). The first positive bucket over spot is 7,760, and the largest positive strikes are far away: 8,000 (+$3.2B), 7,900 (+$2.4B) and 7,850 (+$1.7B).
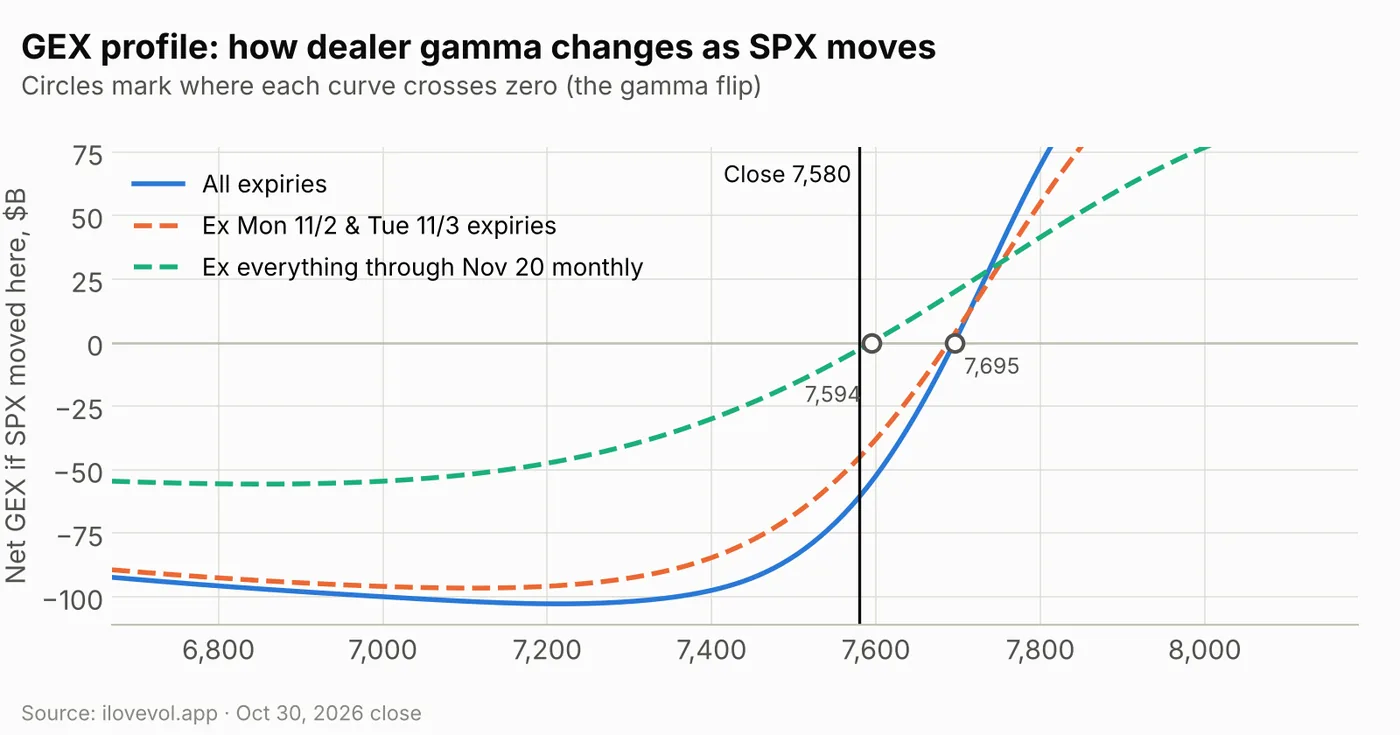
The modeled profile crosses zero near 7,695, close to the site's 7,689 flip, and reads about −$61B at the close. It bottoms near −$103B around 7,211, so there is little modeled support until well under 7,300.
Monday and Tuesday don't change the picture. Remove the Nov 2 and Nov 3 expiries and the flip is still near 7,689, with about −$45B at spot.
The longer-dated book has gone neutral. Strip out everything through the Nov 20 monthly and modeled gamma at spot is about −$2.6B, with a flip near 7,594, just 14 points over the close. On Thursday the same curve was about +$24B long. The cushion beyond November is gone.
Weekly vs monthly: short gamma in every window
Splitting gamma by expiry window (the numbers are in the dealer-gamma table under the scoreboard) shows the close below the flip in all three windows, and the 8–30 day expiries now carry as much short gamma as the weekly ones. Weekly = contracts expiring within 7 calendar days; Monthly = within 30 days.
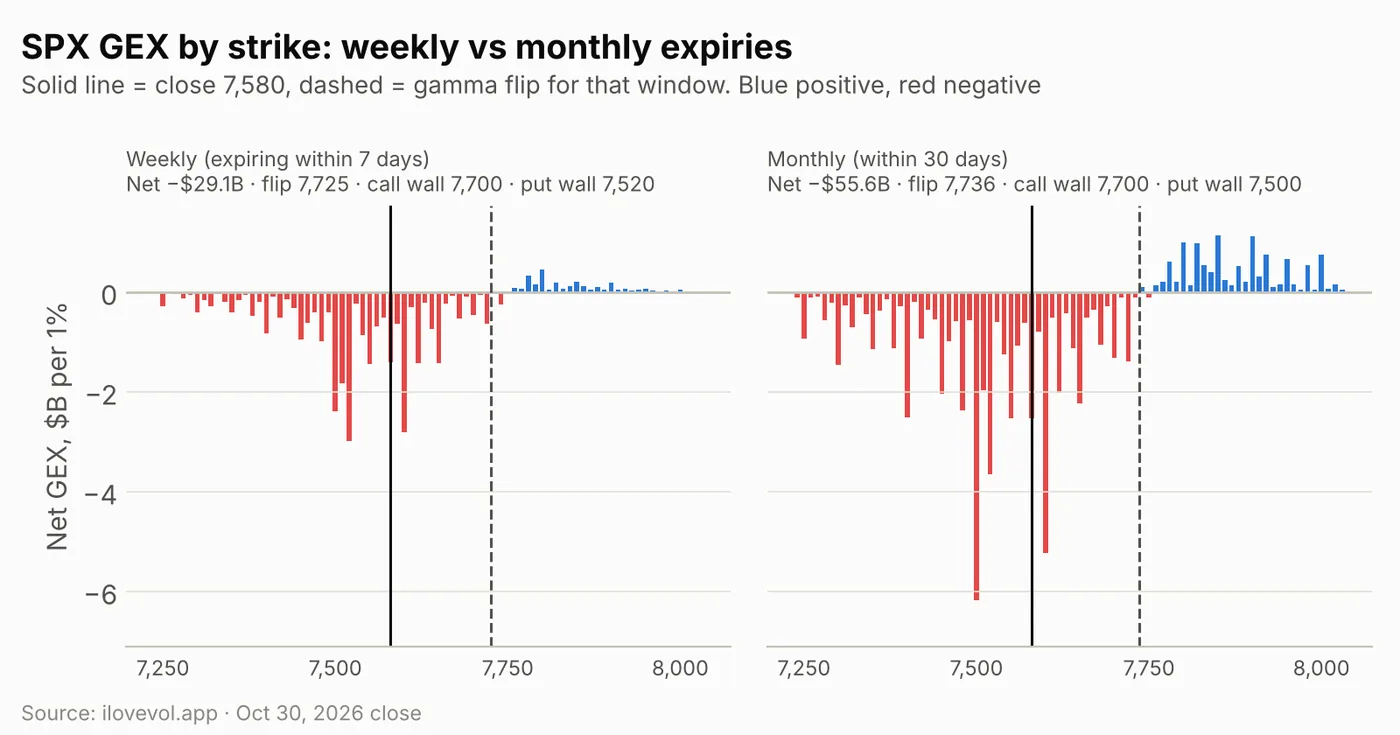
SPX weekly: the next 7 days carry −$29.1B, little changed from −$30.2B and about 54% of the all-expiry total. The window holds five expiries, Nov 2 to Nov 6, which cover Apple and Palantir, the midterm vote, AMD and the October jobs report. Its flip is 7,725, 145 points above the close. The call wall is 7,700 and the put wall 7,520. The largest weekly buckets are 7,520 (−$3.0B), 7,600 (−$2.8B) and 7,500 (−$2.4B); the biggest positive one, 7,800, is only +$0.5B.
SPX monthly: the 30-day window is −$55.6B (−$48.3B on Thursday), with the flip at 7,736, the call wall at 7,700 and the put wall at 7,500. Expiries 8–30 days out add about −$26.5B on top of the weekly book. Expiries beyond 30 days are net long only about $1.7B, down from about $17B on Thursday, so they no longer offset much of the near-term short gamma.
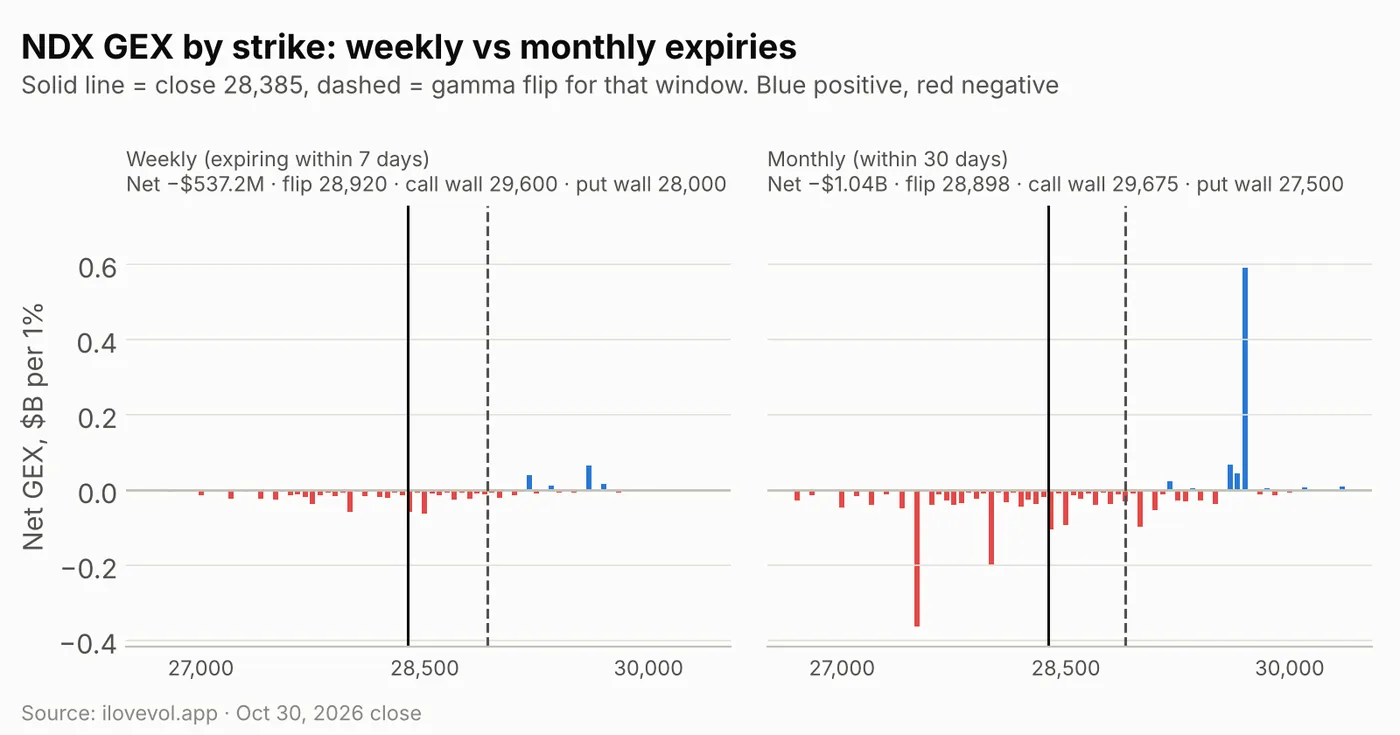
NDX fell 3.46% to 28,385 and its gamma turned negative: −$2.00B in total, from +$0.34B. It closed 801 points under its 29,186 flip. Both near-term windows flipped too: weekly −$0.54B (flip 28,920, call wall 29,600, put wall 28,000) and monthly −$1.04B (flip 28,898, call wall 29,675, put wall 27,500). The largest monthly buckets are 29,700 (+$0.59B), now 1,300 points over the close, and 27,500 (−$0.36B) below it.
RUT fell 1.66% to 2,812 and its gamma went from +$0.84B to −$0.53B. It closed 26 points under its 2,838 flip, with the call wall at 2,850 and the put wall at 2,800.
3. The VIX complex: the front catches up
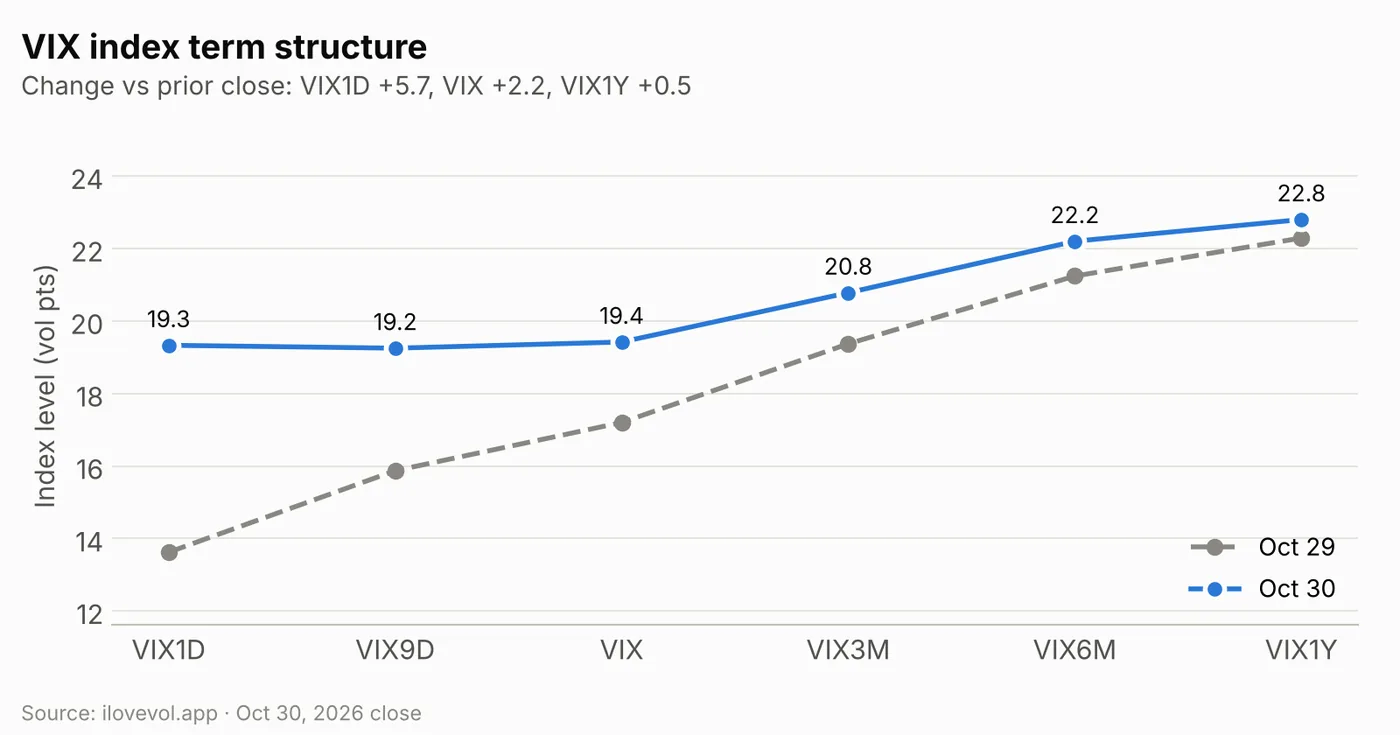
The index curve rose most at the front. VIX1D jumped 5.71 to 19.33, VIX9D 3.38 to 19.25 and VIX 2.22 to 19.42. VIX3M gained 1.41 to 20.78, VIX6M 0.96 to 22.20 and VIX1Y 0.51 to 22.80. The first three points are now flat at about 19.3, and the gap from VIX1D to VIX1Y shrank to 3.5 points from 8.7 on Thursday.
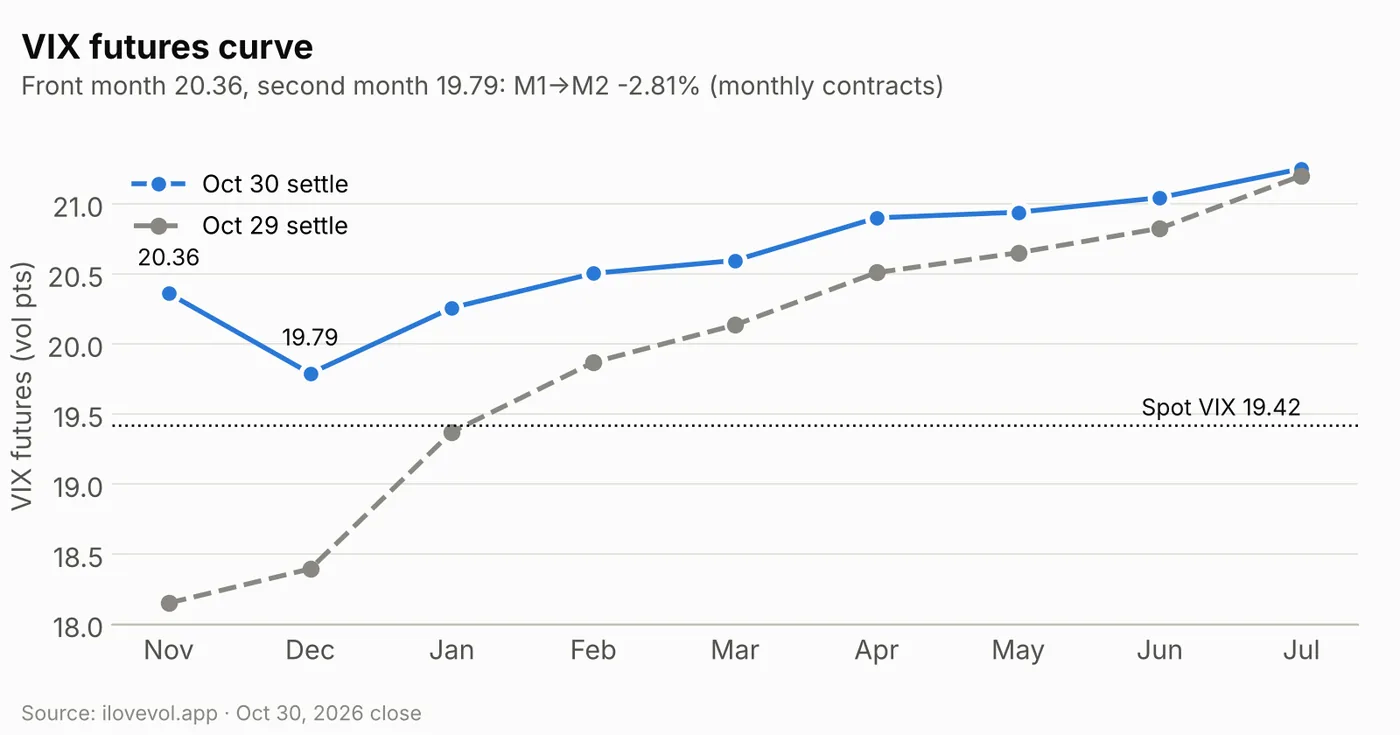
Futures moved the same way. November settled at 20.36, up 2.21, and December at 19.79, up 1.39, so M1→M2 turned negative at −2.81% from +1.34%. Past December the curve is upward-sloping again: January 20.26, then gradually higher to 21.25 in July, which barely moved (+0.05). The November contract, which settles on Nov 18, now prices more than the months on either side of it. It sits 4.8% over spot (5.5% on Thursday). VVIX rose 8.4 to 106.4.
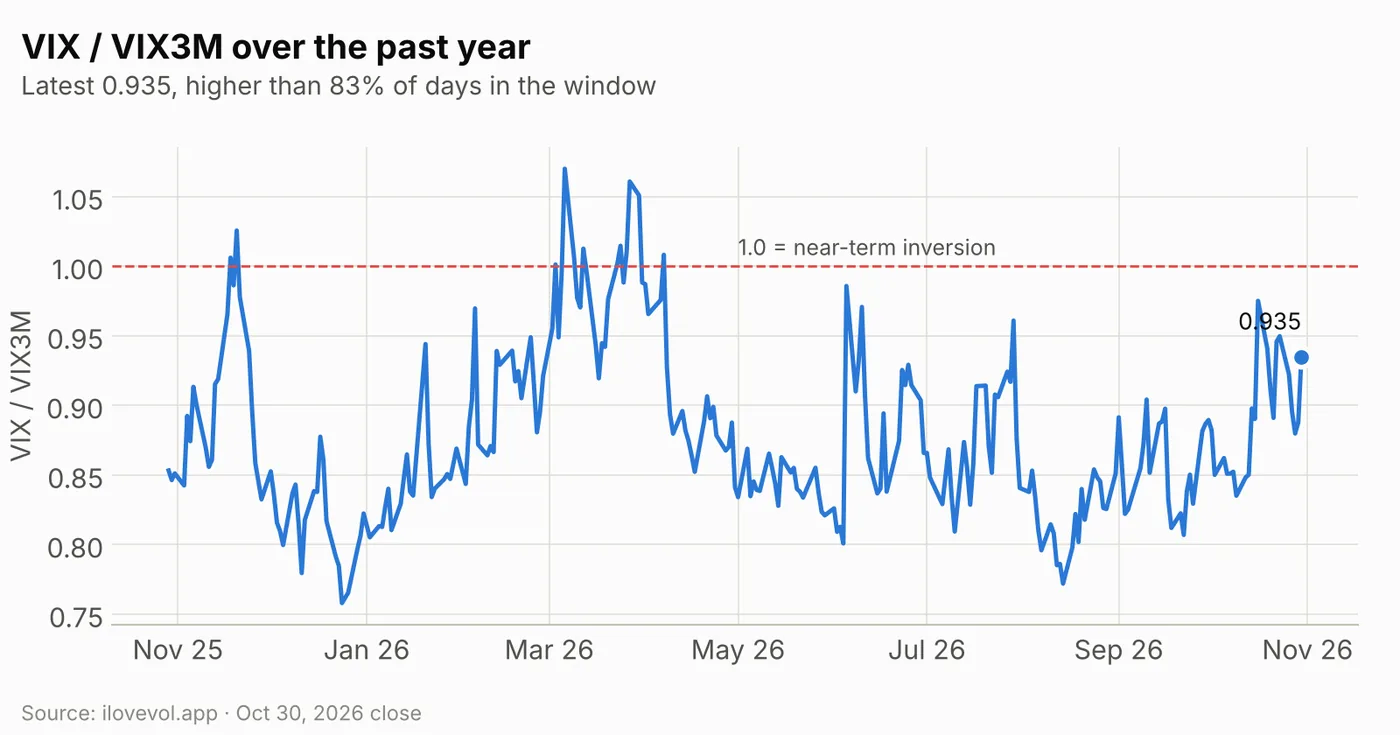
VIX/VIX3M rose to 0.935 from 0.888, higher than 83% of the past year's sessions (64% on Thursday) but still under the 1.0 line where the near-term index curve inverts.
4. Implied vs realized: realized wakes up
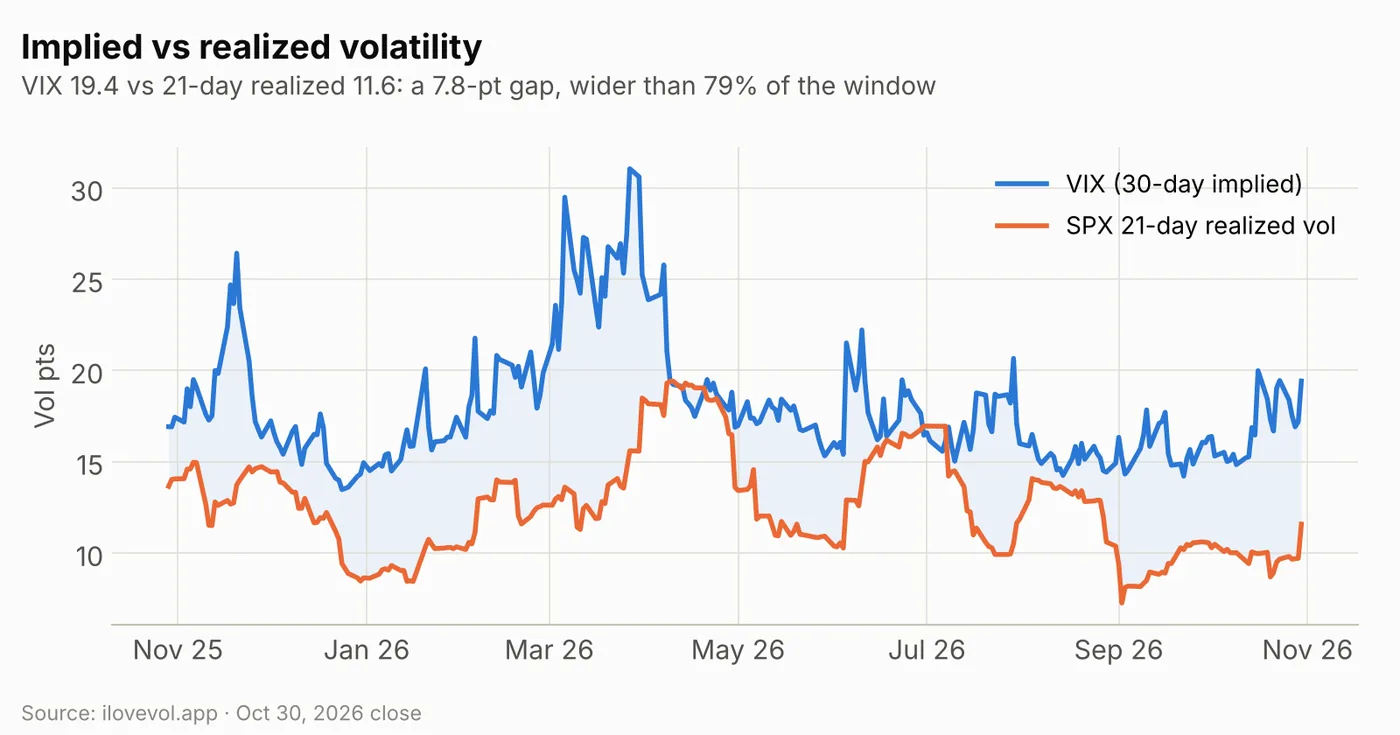
SPX 21-day realized vol jumped to 11.6 from 9.7 as Friday's 1.8% drop entered the window. VIX rose by more, so the gap widened to 7.8 points from 7.5, wider than 79% of the past year (77% on Thursday).
5. The SPX surface: steeper skew, a priced-up week
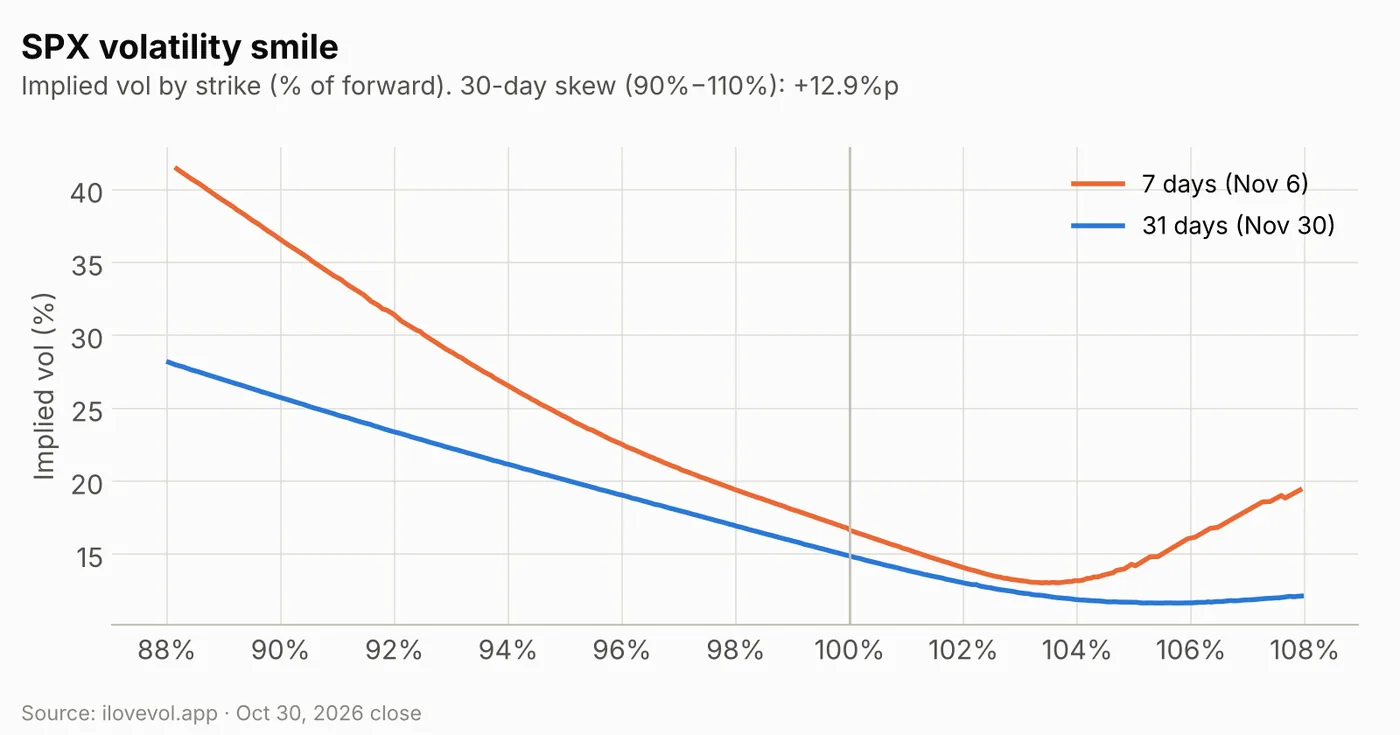
Thirty-day ATM IV rose to 14.9% from 13.2% and 30-day skew (90% vs 110%) steepened to 12.9 points from 11.6. The 90-day vs 30-day term slope is only +0.4 points, almost flat. The 7-day smile (Nov 6) has 88% puts above 40% vol and a call wing that turns up from about 104%; the 31-day curve (Nov 30) is about 28% at 88% and nearly flat on the call side.
The expiry table shows where the premium sits. ATM IV is 11.7% for Monday Nov 2, the lowest on the curve, then 13.9% for Nov 3 (after Apple and Palantir report Monday evening), 15.7% for Nov 4 (the first expiry after the midterm vote and AMD), 16.1% for Nov 5 and 16.6% for Nov 6, jobs report day. As a rough back-of-the-envelope, that implies forward vol near 19% for Wednesday's session and about 18.5% for Friday's, against about 16% for Tuesday's. Through Nov 6 the market prices roughly a 2.3% (about 175-point) move.
6. Cross-asset Vol Sentiment: US equities join the low end
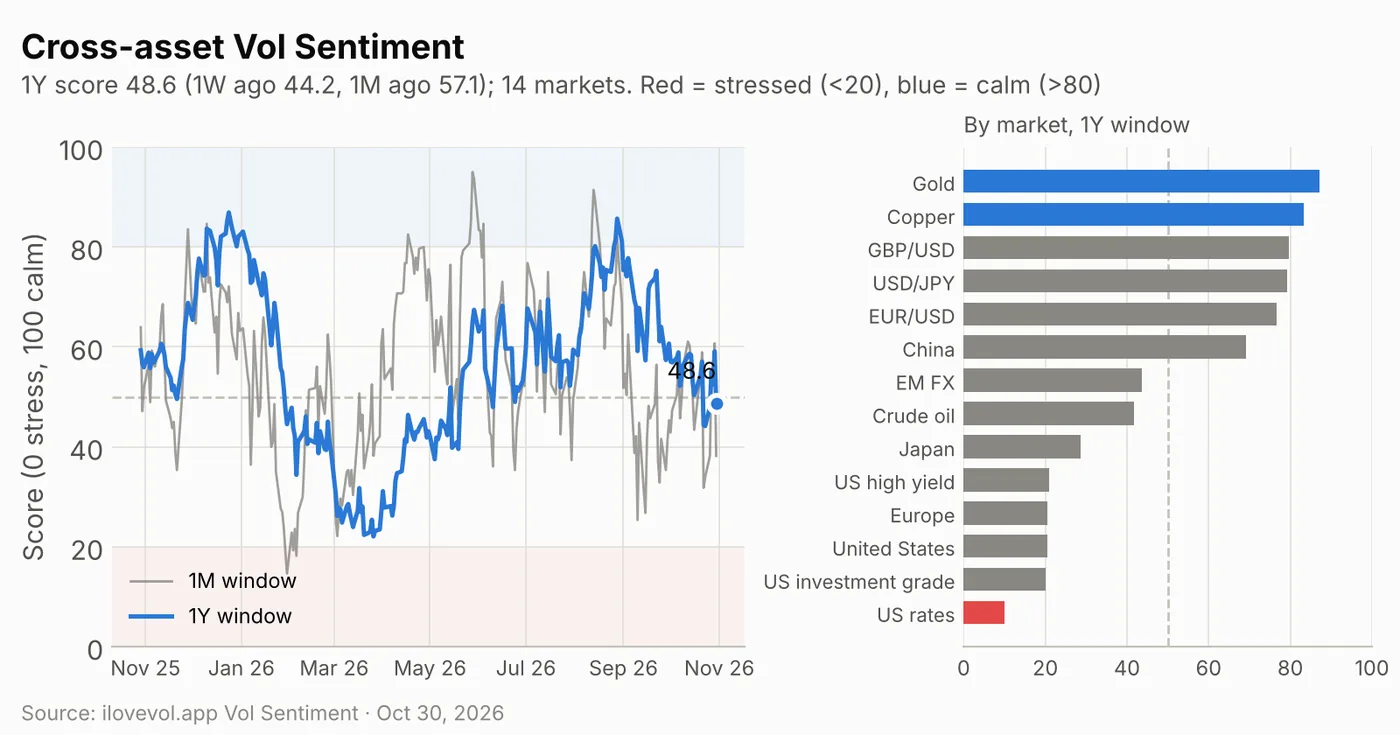
The cross-asset Vol Sentiment score places volatility in 14 equity, currency, rates, credit and commodity markets within its own one-year range (0 = stress, 100 = calm). On the one-year window it fell to 48.6 from 58.0 on Thursday, just under 50. That is above 44.2 a week ago but below 57.1 a month ago, and higher than 32% of the past year's sessions. The shorter windows are weaker: 38.2 on one month and 29.3 on three months.
US rates (10.0) remain the only market in the stressed zone, but four others now sit right on the line: US investment grade (20.0), US equities (20.4, from 45.6), Europe (20.4) and US high yield (20.8). The calmest are gold (87.1) and copper (83.3), followed by GBP/USD (79.6) and USD/JPY (79.2). Next to the SPX picture, the move was concentrated in US equities, credit and European equities, while currencies and metals stayed calm. It is context, not a trading signal.
Calendar: the week ahead
Economic data & Fed
| Date | Time (ET) | Event | Note |
|---|---|---|---|
| Mon Nov 2 | 10:00 (expected) | ISM manufacturing (Oct) | Nov 2 expiry 11.7% ATM, the lowest on the curve |
| Tue Nov 3 | 10:00 | JOLTS job openings (Sep) | Election Day; Nov 3 expiry 13.9% ATM |
| Wed Nov 4 | 10:00 (expected) | ISM services (Oct) | Nov 4 expiry 15.7% ATM |
| Thu Nov 5 | 8:30 | Weekly jobless claims | |
| Fri Nov 6 | 8:30 | October jobs report | Nov 6 expiry 16.6% ATM, the week's highest; September payrolls were +29k |
| Wed Nov 18 | 14:00 | FOMC minutes (Oct 27–28 meeting) | Markets lean toward a December hike |
Earnings
| Date | Timing | Companies | Note |
|---|---|---|---|
| Mon Nov 2 | Before open | Marriott, IDEXX | |
| Mon Nov 2 | After close | Apple, Palantir, Vertex Pharmaceuticals | Reaction in the Nov 3 expiry (13.9% ATM vs 11.7% Nov 2) |
| Tue Nov 3 | Before open | Shopify, Pfizer, Apollo, Eaton, Yum! Brands | |
| Tue Nov 3 | After close | AMD, Amgen, Arista Networks, Booking | Reaction in the Nov 4 expiry (15.7% ATM) |
| Wed Nov 4 | Before open | Uber, CVS Health, Datadog | McDonald's expected, time not confirmed |
| Wed Nov 4 | After close | Qualcomm, AppLovin, DoorDash | Arm also reports Nov 4, time not confirmed |
| Thu Nov 5 | Before open | ConocoPhillips, Cigna, Duke Energy | |
| Thu Nov 5 | After close | Airbnb, Cloudflare, Atlassian, Monster Beverage |
Volatility dates (expirations, events)
| Date | Event | Note |
|---|---|---|
| Sun Nov 1 | US daylight saving time ends | US data and the open move one hour later in Asia/Europe time |
| Tue Nov 3 | US midterm elections | Nov 4 expiry (first after the vote) 15.7% ATM vs 13.9% Nov 3 |
| Fri Nov 6 | Weekly SPX expiry with the jobs report | 16.6% ATM, about a 2.3% move priced through Nov 6 |
| Wed Nov 18 | VIX November futures and options expiration | Nov future 20.36, above Dec (19.79) |
| Fri Nov 20 | SPX November monthly expiration | Removing everything through it leaves modeled gamma at spot about −$2.6B |
What I'm watching next week
- 7,689–7,736. The all-expiry flip (7,689), the weekly flip (7,725) and the monthly flip (7,736), with the 7,700 call wall in both near-term windows. SPX is 109 points under the bottom of this band; until it gets back above, dealers are short gamma in every window.
- 7,520 and 7,500, then 7,400. The weekly put wall, then the monthly put wall and largest negative strike (−$8.3B), then 7,400 (−$4.9B). Below there, the profile keeps falling toward about −$103B near 7,211.
- Monday's 11.7% vs the rest of the week. Monday's expiry is the cheapest on the curve, while Wednesday (after the vote and AMD) and Friday (jobs) imply forward vol near 19%. Friday's expiry priced about 74 points and SPX moved 140.
- The November VIX future over December. M1→M2 is −2.81%, VVIX is 106.4 and VIX/VIX3M is 0.935 (83rd percentile). A return of November below December would be the first sign the near-term premium is fading.
- NDX under every flip. NDX closed 801 points under its 29,186 flip with −$2.00B of gamma; 28,000 is the put wall in both the all-expiry and weekly windows.
Sources
- Yahoo Finance: Nasdaq, Dow, S&P 500 clobbered as October closes with brutal sell-off
- TheStreet: Stock Market Today (Oct. 30, 2026): Intel, Reddit are latest tech earnings casualties as Nasdaq sinks nearly 3%
- StockTitan: Stock Market Today Live October 30, 2026: Tech stocks fall as Intel has its worst day in decades
- StockTitan: Apple, AMD and Palantir lead the earnings week of November 2
- Earnings Watcher: Earnings implied moves, week of Nov 2–6, 2026
- Tech Insider: Week ahead, midterms, jobs and Fed hike odds
- FedRateCalc: US economic calendar, November 2026 (BLS release dates)
Volatility data: ilovevol.app. GEX assumes dealers are long calls and short puts. VIX futures use settlement prices. Forward vols and the implied move are approximations from expiry ATM IV. Vol Sentiment: ilovevol.app cross-asset score (0 = stress, 100 = calm), one-year window unless noted.
This review is for informational and educational purposes only and is not investment advice. See the disclaimer.
The Daily Vol sends this review to your inbox each trading day: dealer gamma levels, the VIX curves, the SPX vol surface and the levels to watch. Free, one click to unsubscribe.