Home › Blog › Daily Market Review
Daily Market Review · US close
SPX ends 123 points under its gamma flip as GEX hits −$62.6B and VIX9D tops VIX
SPX gave up a 1% morning gain to close down 0.5% at 7,541, and net GEX deepened from −$53.9B to −$62.6B. VIX rose 1.73 to 21.15 while VIX9D jumped above it, and Wednesday's expiry, the first after the vote, carries 22.5% ATM. Here are the levels.
- Oil fell about 8% on US–Iran diplomacy hopes, but chips and AI infrastructure sold off again (Marvell −12.7%, Lumentum −18.6%, Oracle −8.7%). SPX −0.51% to 7,541 and NDX −1.39%; the Dow gained about 0.4%.
- Net GEX fell from −$53.9B to −$62.6B. SPX closed 123 points under its 7,664 flip and under the weekly (7,698) and monthly (7,706) flips. 7,500 is still the largest negative strike (−$8.3B), with the weekly put wall at 7,520.
- VIX rose 1.73 to 21.15 while VIX1D fell 1.43 to 17.90. VIX9D (22.46) is now above VIX: the nine-day window holds the midterms, AMD and jobs. The Nov 4 expiry carries 22.5% ATM, the curve's high.
Scoreboard
| Close | Chg | Prev | |
|---|---|---|---|
| SPX | 7,541 | −0.51% | 7,580 |
| NDX | 27,990 | −1.39% | 28,385 |
| VIX | 21.15 | +1.73 | 19.42 |
| VIX1D | 17.90 | −1.43 | 19.33 |
| VVIX | 110.5 | +4.0 | 106.4 |
| VX Nov / Dec | 20.38 / 19.84 | −2.61% M1→M2 | −2.81% |
| VIX / VIX3M | 0.979 | +0.044 | 0.935 |
| 30D ATM IV / skew | 16.3% / 13.9 | +1.4 / +1.0 | 14.9% / 12.9 |
| Window | Net GEX | Chg | Prev | Flip | Call wall | Put wall | |
|---|---|---|---|---|---|---|---|
| SPX | All | −$62.6B | −$8.7B | −$53.9B | 7,664 | 8,000 | 7,000 |
| SPX | Weekly | −$34.3B | −$5.2B | −$29.1B | 7,698 | 7,650 | 7,520 |
| SPX | Monthly | −$62.5B | −$6.9B | −$55.6B | 7,706 | 7,700 | 7,500 |
| NDX | All | −$1.78B | +$0.22B | −$2.00B | 28,789 | 29,675 | 27,500 |
| NDX | Weekly | −$0.55B | −$0.01B | −$0.54B | 28,414 | 28,700 | 27,500 |
| NDX | Monthly | −$1.28B | −$0.24B | −$1.04B | 28,702 | 29,675 | 27,500 |
Dealer gamma by expiry window. All = every listed expiry; Weekly = contracts expiring within 7 calendar days; Monthly = within 30 days. Net GEX in $ per 1% move.
1. The tape: oil breaks, chips break again
Monday opened as a relief day. Oil fell sharply on reports that the US and Iran are looking for a diplomatic way out of the Middle East conflict, and the S&P 500 traded about 1% higher in the morning. The gains did not last. Selling in chips and AI infrastructure returned in the afternoon: Marvell lost 12.7% after agreeing to buy Lumentum in an all-stock deal valued at about $115 billion including debt, and Lumentum fell 18.6%. Oracle dropped 8.7% after announcing plans to raise new equity alongside debt, adding to questions about how the AI build-out is financed. CoreWeave fell 9.2% and Nvidia 1.3%.
The S&P 500 closed down 0.51% at 7,541 and the Nasdaq Composite fell 1.07% to 25,164. The Nasdaq-100 lost 1.39% and the Russell 2000 0.21% to 2,806, while the Dow gained about 0.4% to near 51,980. Airlines (United +4.8%) and consumer discretionary led on lower fuel costs, and Amazon rose 2.2%; energy lagged, with Exxon down 4.0%. IDEXX jumped 21.9% after raising its 2026 forecast.
WTI fell about 7.7% to near $96 and Brent about 7.6% to near $105. The 10-year yield eased about 3.5 basis points to near 4.89% and gold rose about 1.5%. October ISM manufacturing rose to 55.5 from 54.5, ahead of forecasts, with prices paid easing to 75.2. Futures still price roughly a 76% chance of a December hike. After the close, Palantir reported revenue up 96% and raised its outlook, and Apple beat on revenue in John Ternus' first quarter as CEO.
Why it matters for vol: VIX rose 1.73 on a day SPX fell only 0.5%, and most of the bid sat in the next nine days: Tuesday's vote, AMD that evening, the Treasury refunding and Friday's jobs report. Monday's own expiry priced about 56 points (11.7% ATM) and SPX finished 39 points lower.
2. Dealer gamma: shorter again
Net GEX across all expiries fell from −$53.9B to −$62.6B per 1% move. The flip came down to 7,664 (7,689 on Friday), but SPX closed 123 points (1.6%) under it, compared with 109 points under on Friday. Dealers are short gamma in every window, so their hedging tends to add to moves rather than damp them.
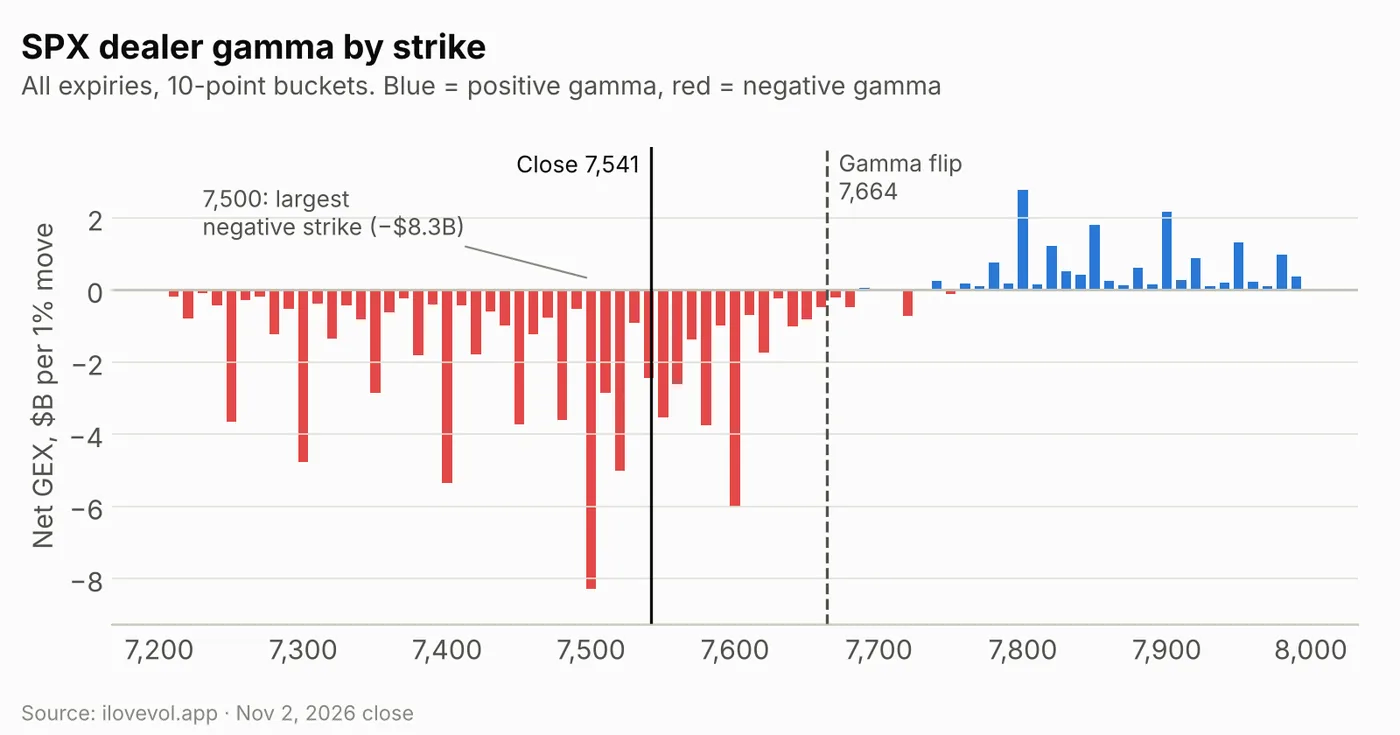
Every bucket from 7,250 to 7,680 is negative. The largest are 7,500 (−$8.3B), 7,600 (−$6.0B), 7,400 (−$5.4B), 7,520 (−$5.0B) and 7,300 (−$4.8B). Meaningful positive gamma only starts at 7,800 (+$2.8B), then 7,900 (+$2.2B) and 7,850 (+$1.8B).
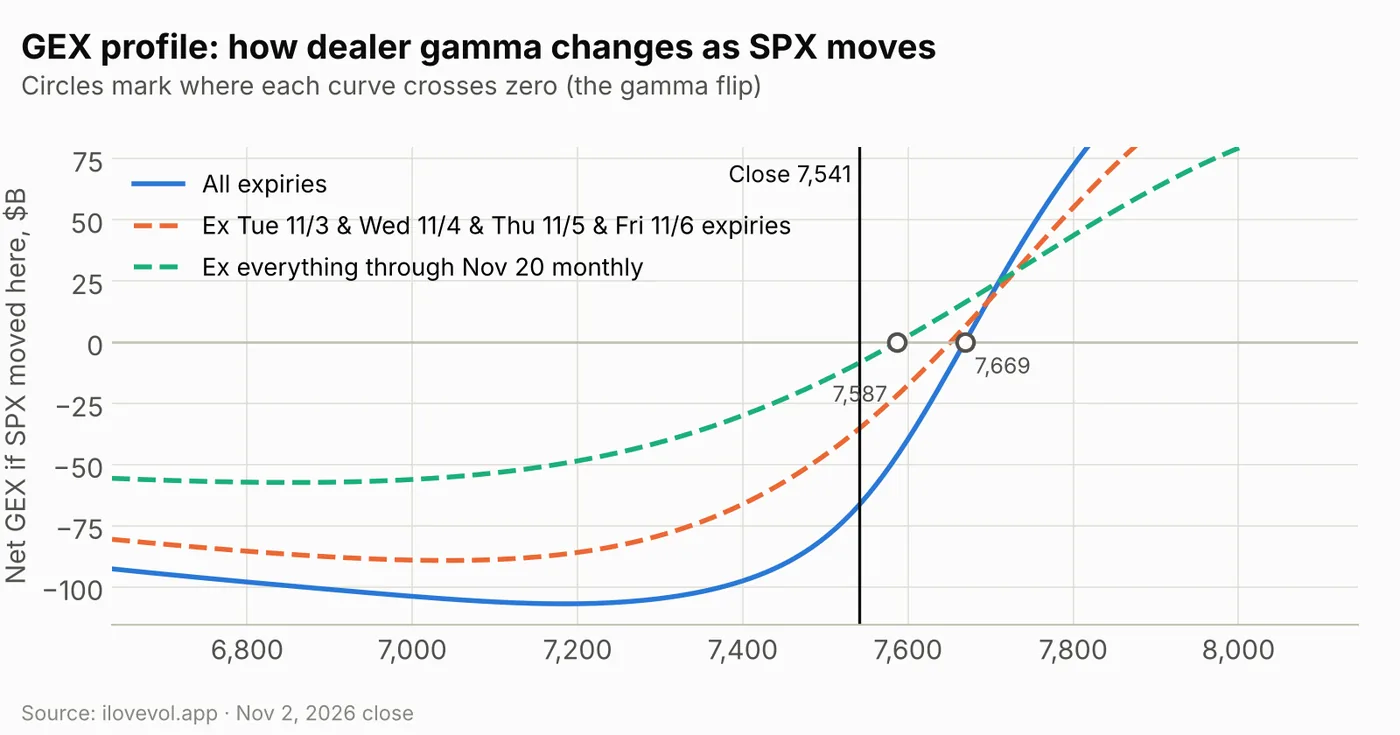
The modeled profile crosses zero near 7,669, close to the site's 7,664 flip, and reads about −$66B at the close. It keeps falling to a low near −$107B around 7,183, so there is little modeled support until well below 7,300.
This week's expiries carry about half of it. Without the Nov 3–6 expiries the flip only moves to about 7,651, with roughly −$35B at spot.
The longer-dated book has tipped short. Without everything through the Nov 20 monthly, modeled gamma at spot is about −$8.3B (−$2.6B on Friday), with a flip near 7,587, 46 points over the close.
Weekly vs monthly: the event week holds the most
The close is under the flip in all three windows (numbers in the dealer-gamma table under the scoreboard), and both the weekly and the 8–30 day buckets got shorter.
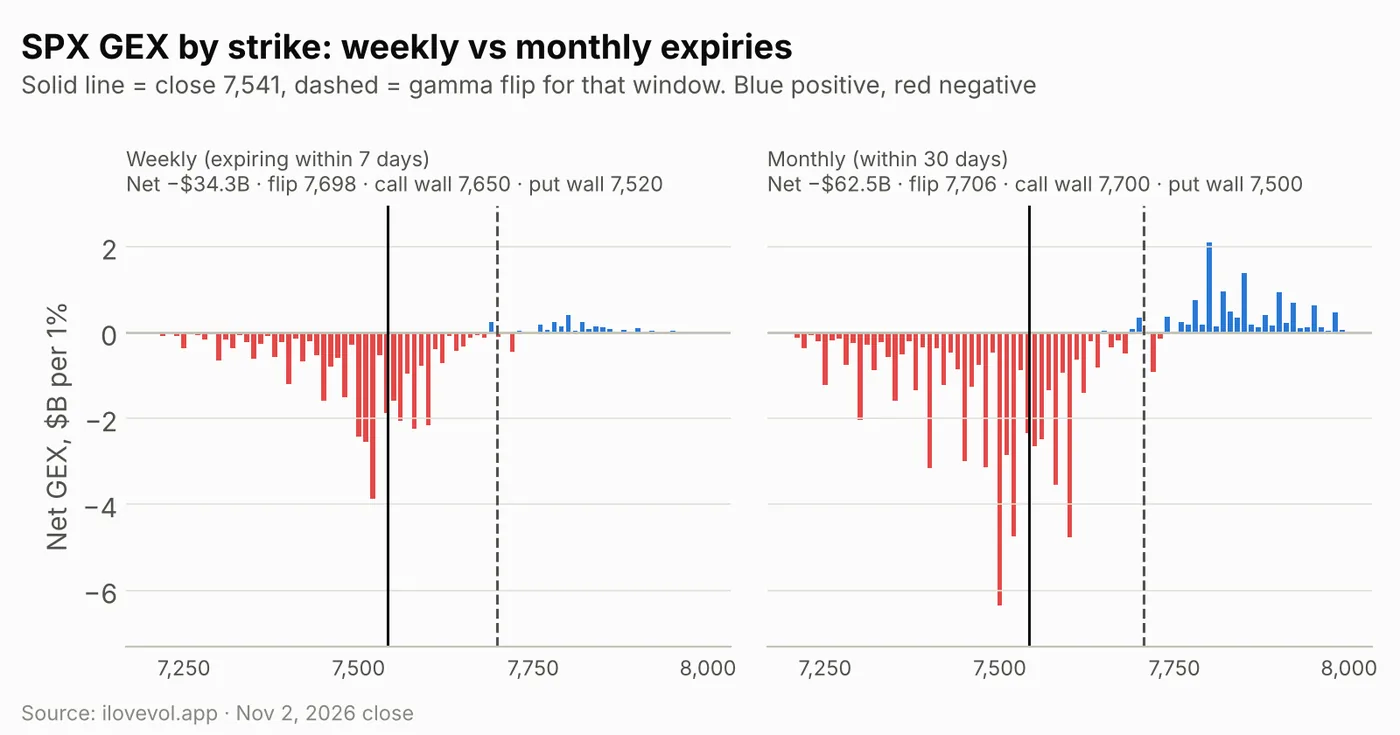
SPX weekly: the next 7 days carry −$34.3B, from −$29.1B, about 55% of the total. The window holds five expiries, Nov 3 to Nov 9, covering the vote, AMD and the jobs report. Its flip is 7,698, 157 points over the close. The call wall dropped to 7,650 (7,700 on Friday) and the put wall stays at 7,520, also the largest weekly bucket (−$3.9B). The biggest positive weekly bucket, 7,800, is only +$0.4B.
SPX monthly: the 30-day window is −$62.5B (−$55.6B on Friday), with the flip at 7,706, the call wall at 7,700 and the put wall at 7,500. Expiries 8–30 days out add about −$28.2B to the weekly book, and expiries beyond 30 days now net to roughly zero (about −$0.1B, from +$1.7B), so nothing further out offsets the near-term short gamma.
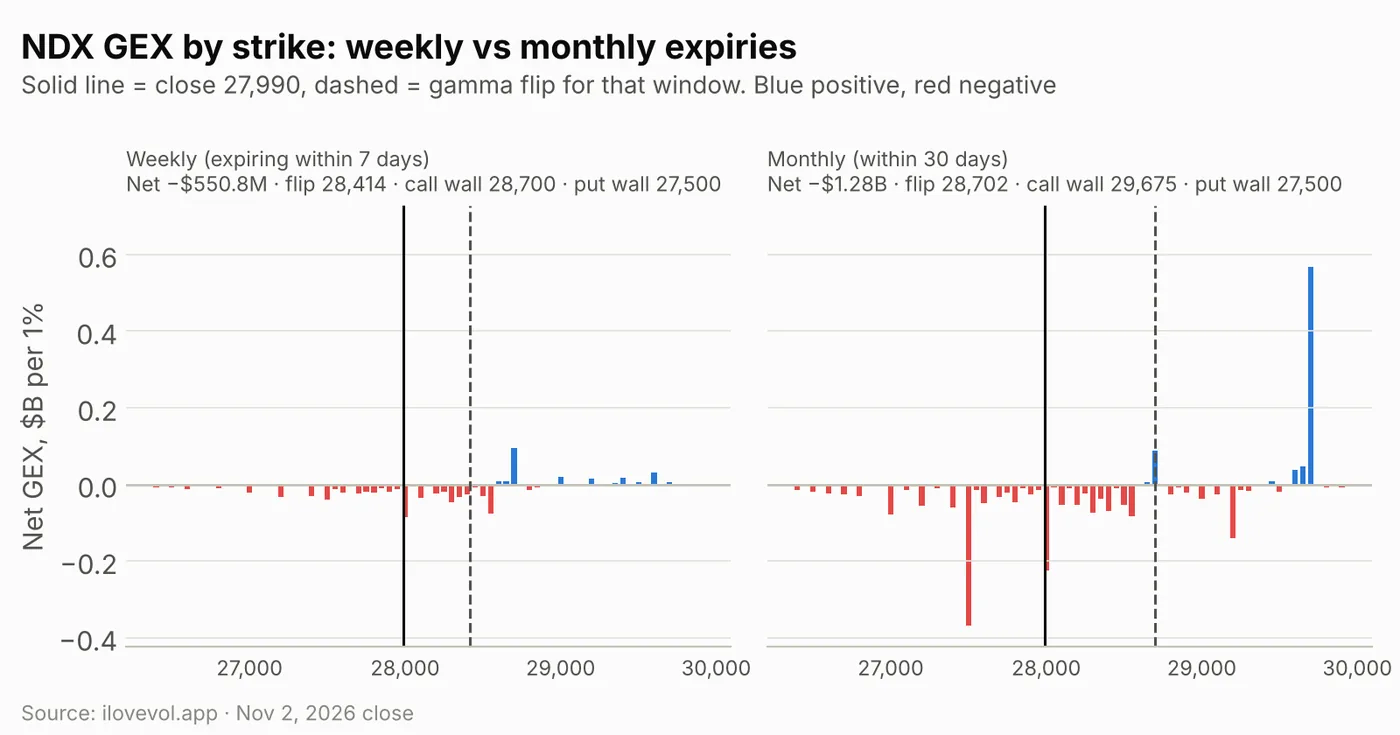
NDX fell 1.39% to 27,990 with total gamma of −$1.78B (−$2.00B on Friday), 799 points under its 28,789 flip. Weekly is −$0.55B (flip 28,414, call wall 28,700, put wall 27,500) and monthly −$1.28B (flip 28,702, call wall 29,675, put wall 27,500). The monthly book's largest buckets are 29,700 (+$0.57B), 1,700 points over the close, and 27,500 (−$0.37B).
RUT slipped 0.21% to 2,806 with gamma of −$0.56B (−$0.53B on Friday). It closed 34 points under its 2,840 flip, with the call wall at 2,850 and the put wall at 2,800.
3. The VIX complex: the nine-day point takes over
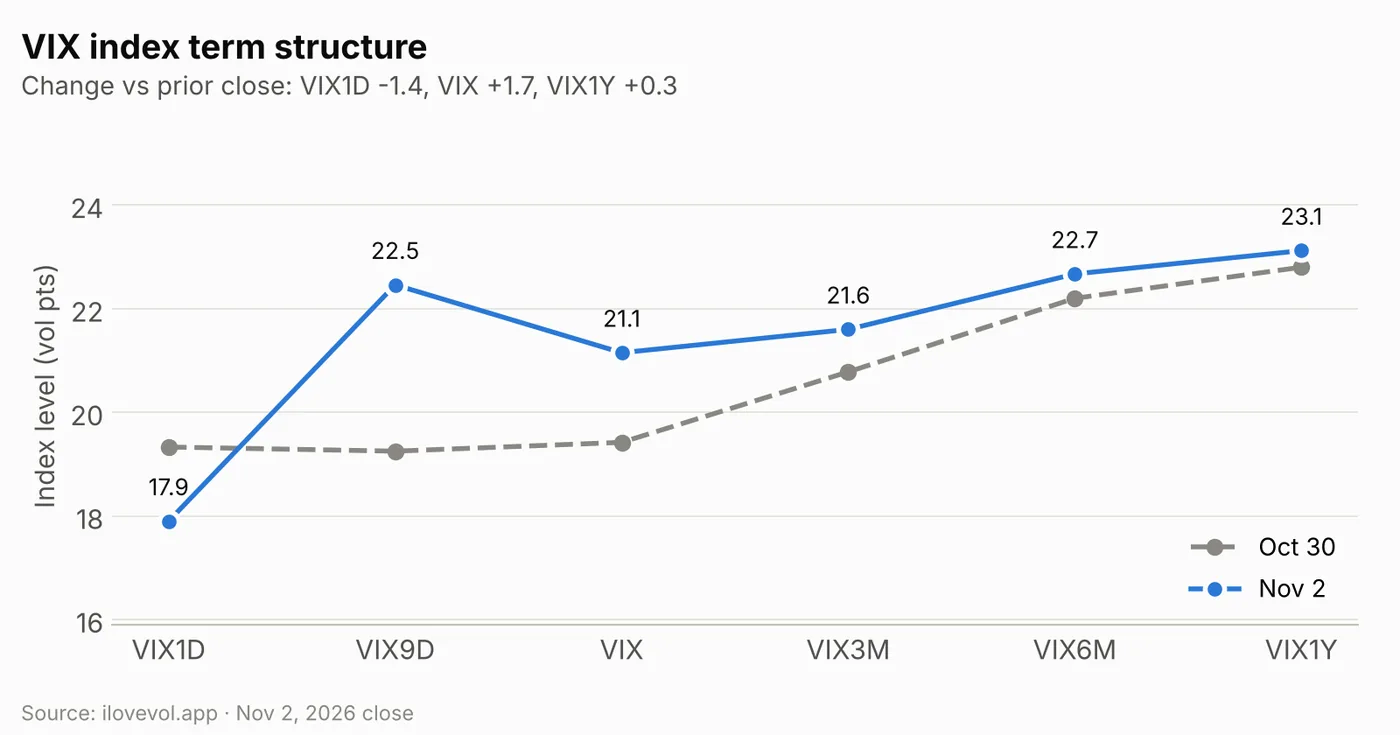
The index curve now has a hump. VIX1D fell 1.43 to 17.90 as Monday's session passed, but VIX9D jumped 3.21 to 22.46, 1.31 points above VIX (21.15, +1.73). Further out the moves were smaller: VIX3M +0.82 to 21.60, VIX6M +0.47 to 22.67 and VIX1Y +0.32 to 23.12. The market is paying most for the next nine days, not for the next three months.
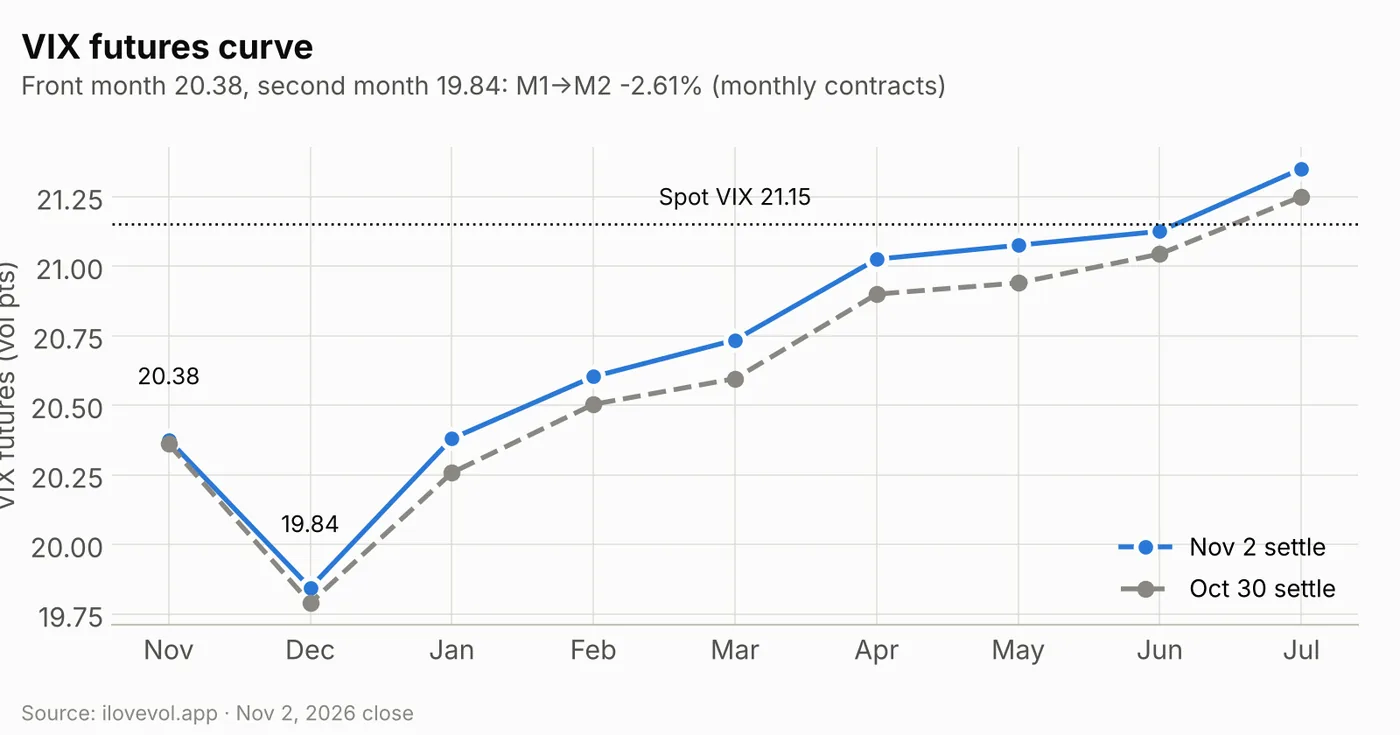
Futures barely moved while spot rose. November settled at 20.38 (+0.01) and December at 19.84 (+0.06), so M1→M2 stayed negative at −2.61% (−2.81% on Friday); the back months edged up about 0.1 point. The change is that spot VIX is now 0.77 point above the November contract, which settles on Nov 18; on Friday November sat 0.94 over spot. Futures price VIX lower by mid-November than it is today. VVIX rose 4.0 to 110.5.
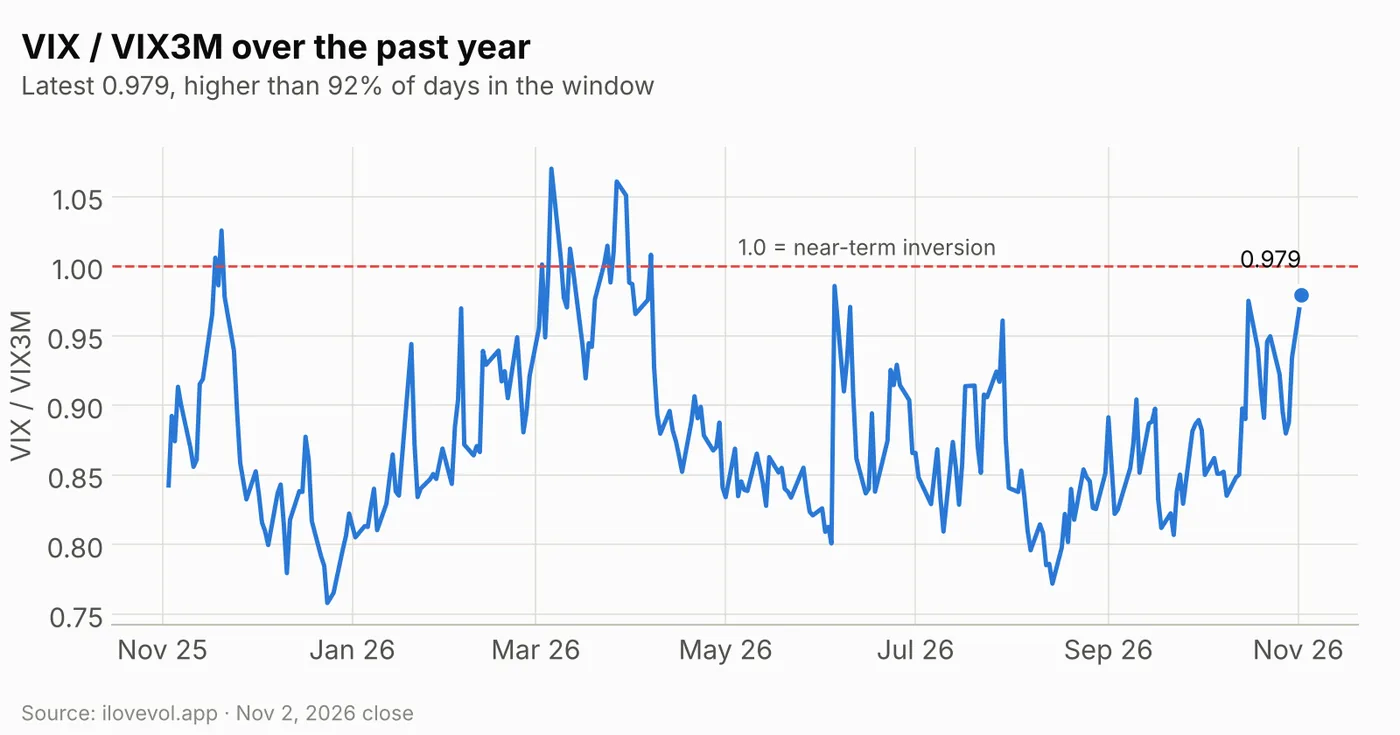
VIX/VIX3M rose to 0.979 from 0.935, higher than 92% of the past year's sessions (83% on Friday) and close to the 1.0 line where the near-term index curve inverts.
4. Implied vs realized: the gap widens
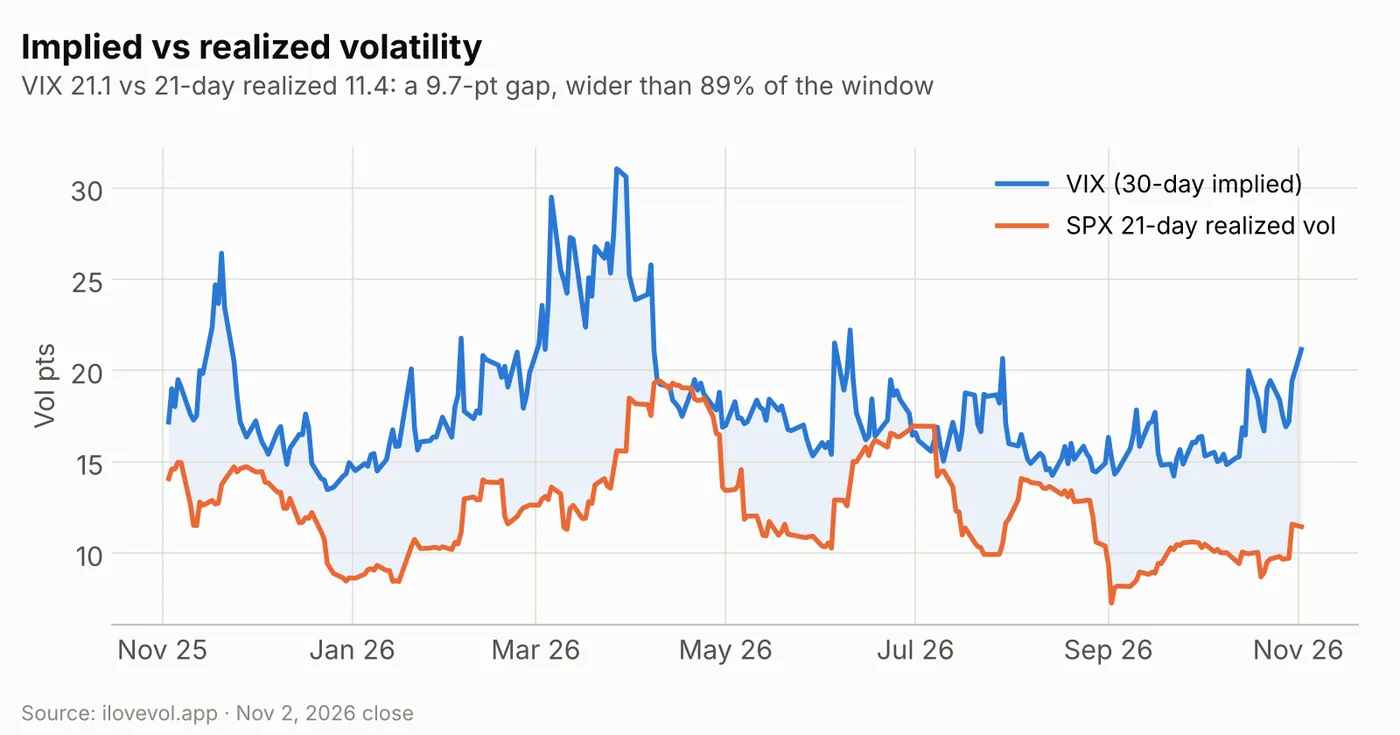
SPX 21-day realized vol eased to 11.4 from 11.6. With VIX up, the gap widened to 9.7 points from 7.8, wider than 89% of the past year (79% on Friday).
5. SPX surface: a priced-up event week
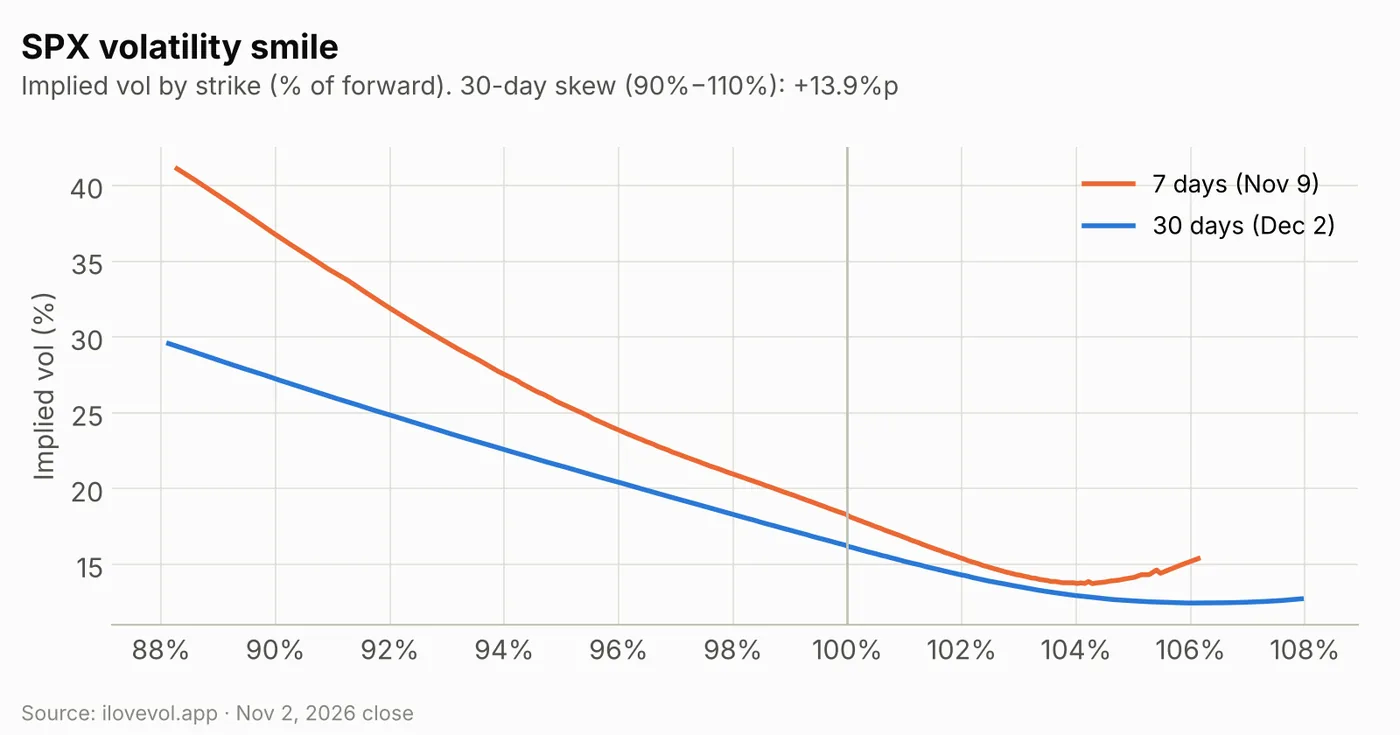
Thirty-day ATM IV rose to 16.3% from 14.9% and 30-day skew (90% vs 110%) steepened to 13.9 points from 12.9. The 90-day minus 30-day slope turned negative at −0.4 points (+0.4 on Friday). The 7-day smile (Nov 9) has 88% puts above 40% vol and bottoms near 14% around 104%; the 30-day curve (Dec 2) runs from about 30% at 88% to a flat call side near 12.5%.
ATM IV is 20.6% for Tuesday Nov 3 (Election Day), 22.5% for Nov 4, the first expiry after the vote and AMD and the highest on the curve, 21.9% for Nov 5 and 22.1% for Nov 6, jobs day. Roughly, that implies forward vol near 24% for Wednesday's session and about 23% for Friday's, against about 21% for Tuesday's. Through Nov 6 the market prices about a 2.8% (about 210-point) move. After that the curve drops back: 18.6% for Nov 9 and 17.6% for the Nov 20 monthly.
6. Cross-asset Vol Sentiment: four US markets in the stressed zone
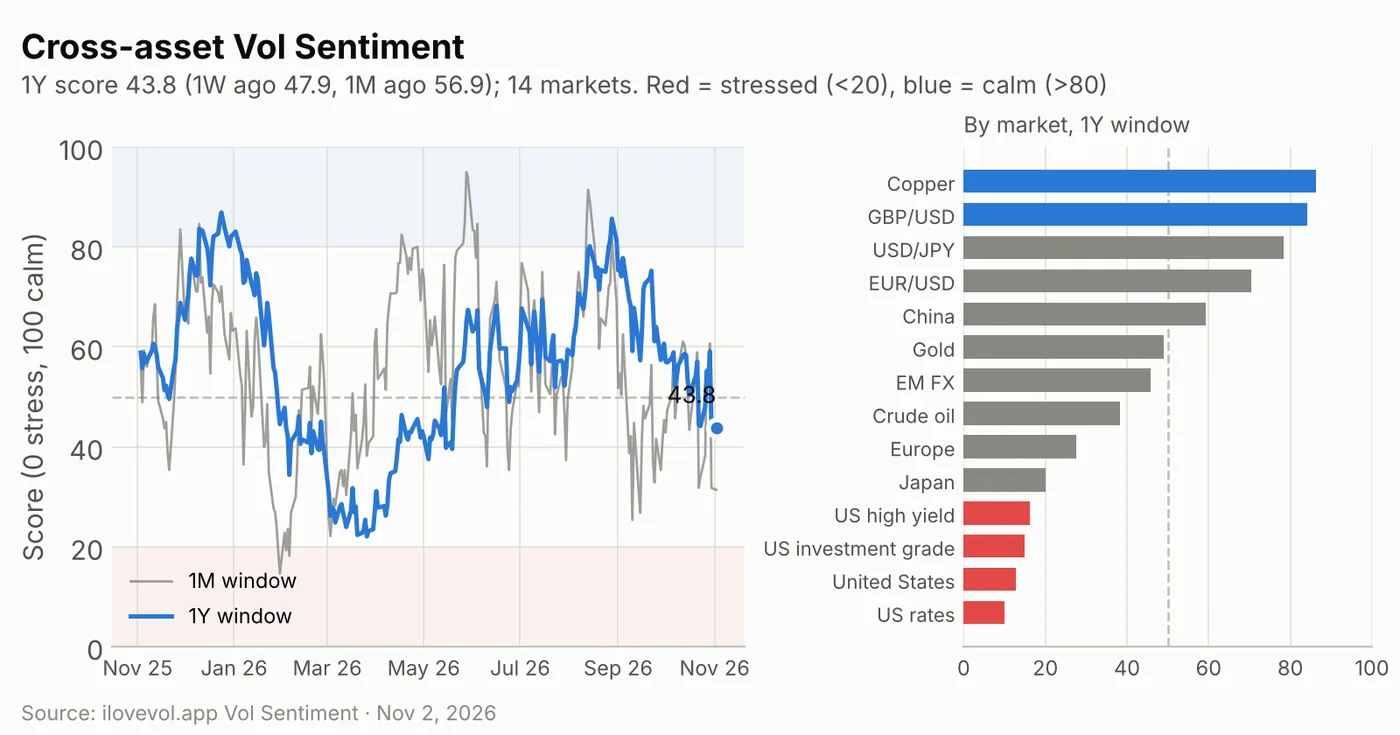
The cross-asset Vol Sentiment score places volatility in 14 equity, currency, rates, credit and commodity markets within its own one-year range (0 = stress, 100 = calm). On the one-year window it slipped to 43.8 from 44.3 on Friday, below 47.9 a week earlier and 56.9 a month earlier, and higher than only 26% of the past year's sessions. The shorter windows are weaker: 31.4 on one month and 23.9 on three months.
Four markets are now in the stressed zone (under 20), all of them in the US: rates (10.0), equities (12.7), investment grade (15.0) and high yield (16.2). Japan (20.0) sits on the line and Europe is at 27.5. The calmest are copper (86.2) and GBP/USD (84.2), followed by USD/JPY (78.3); gold has come down to 49.0. Next to the SPX picture, the strain is concentrated in US equities, credit and rates, while currencies and copper stay calm. It is context, not a trading signal.
Calendar: the week ahead
Economic data & Fed
| Date | Time (ET) | Event | Note |
|---|---|---|---|
| Tue Nov 3 | 10:00 | JOLTS job openings (Sep); factory orders (Sep) | Election Day; Nov 3 expiry 20.6% ATM |
| Wed Nov 4 | 8:15 (expected) | ADP employment (Oct) | |
| Wed Nov 4 | 8:30 | Treasury quarterly refunding statement; trade balance (Sep) | Nov 4 expiry 22.5% ATM, the highest on the curve |
| Wed Nov 4 | 10:00 | ISM services (Oct) | Manufacturing ISM rose to 55.5 on Monday |
| Thu Nov 5 | 7:00 (expected) | Bank of England decision | |
| Thu Nov 5 | 8:30 | Jobless claims; Q3 productivity and unit labor costs | Fed's Hammack and Barkin also speak (times –) |
| Fri Nov 6 | 8:30 | October jobs report | Nov 6 expiry 22.1% ATM; September payrolls were +29k |
| Fri Nov 6 | 10:00 (expected) | University of Michigan sentiment (Nov, prelim) | Fed's Bowman 12:15; Logan, Williams, Musalem (times –) |
| Wed Nov 18 | 14:00 | FOMC minutes (Oct 27–28 meeting) | Futures price about a 76% chance of a December hike |
Earnings
| Date | Timing | Companies | Note |
|---|---|---|---|
| Tue Nov 3 | Before open | Shopify, Pfizer, Apollo, Eaton, Yum! Brands | |
| Tue Nov 3 | After close | AMD, Amgen, Arista Networks, Booking | Reaction in the Nov 4 expiry (22.5% ATM), together with the vote |
| Wed Nov 4 | Before open | Uber, CVS Health, Datadog | McDonald's expected, time not confirmed |
| Wed Nov 4 | After close | Qualcomm, AppLovin, DoorDash | Arm also reports Nov 4, time not confirmed |
| Thu Nov 5 | Before open | ConocoPhillips, Cigna, Duke Energy | |
| Thu Nov 5 | After close | Airbnb, Cloudflare, Atlassian, Monster Beverage |
Volatility dates (expirations, events)
| Date | Event | Note |
|---|---|---|
| Tue Nov 3 | US midterm elections | Results arrive overnight; Nov 4 expiry 22.5% ATM vs 20.6% Nov 3 |
| Fri Nov 6 | Weekly SPX expiry with the jobs report | 22.1% ATM, about a 2.8% move priced through Nov 6 |
| Wed Nov 18 | VIX November futures and options expiration | Nov future 20.38, under spot VIX (21.15), above Dec (19.84) |
| Fri Nov 20 | SPX November monthly expiration | 17.6% ATM; removing everything through it leaves modeled gamma at spot about −$8.3B |
| Thu Nov 26 / Fri Nov 27 | Thanksgiving (closed) / 1:00 pm early close |
What I'm watching
- 7,664–7,706. The all-expiry flip (7,664), the weekly flip (7,698) and the monthly flip (7,706), with the 7,650 weekly call wall and the 7,700 monthly call wall inside the band. SPX is 123 points under the bottom of it; until it gets back above, dealers are short gamma in every window.
- 7,520 and 7,500, then 7,400. The weekly put wall and largest weekly bucket (−$3.9B), then the monthly put wall and largest negative strike (−$8.3B), then 7,400 (−$5.4B). Below there the modeled profile keeps falling toward about −$107B near 7,183.
- The Wednesday and Friday premium. Nov 4 (22.5% ATM) and Nov 6 (22.1%) imply forward vol near 24% and 23% for those sessions, against 18.6% for Nov 9. Monday's expiry priced about 56 points and SPX moved 39.
- VIX9D over VIX, spot over November futures. VIX9D is 1.31 points above VIX and spot VIX is 0.77 over the Nov future, with VIX/VIX3M at 0.979 (92nd percentile) and VVIX at 110.5. If the vote and payrolls pass quietly, the nine-day point is where the premium should come out first.
- The book beyond the monthly. Without everything through Nov 20, modeled gamma at spot is −$8.3B with a flip at 7,587. A return to positive there would be the first sign of a cushion rebuilding.
Sources
- Yahoo Finance: S&P 500 and Nasdaq extend tech sell-off, Dow gains as oil prices plunge (Nov 2, 2026)
- StockTitan: Tech Stocks Pull the Nasdaq Lower in the Stock Market Today Live, November 2, 2026
- 24/7 Wall St.: S&P 500 closes down 0.5% while the Dow gains (Nov 2, 2026)
- CNBC: Apple beats on quarterly revenue in CEO John Ternus' first earnings report
- FatTail: Week ahead, midterms, refunding and jobs, Nov 2–6
- Newsquawk: Weekly economic calendar, 2nd–6th November 2026
- StockTitan: Apple, AMD and Palantir lead the earnings week of November 2
- FedRateCalc: US economic calendar, November 2026 (BLS release dates)
Volatility data: ilovevol.app. GEX assumes dealers are long calls and short puts. VIX futures use settlement prices. Forward vols and implied moves are approximations from expiry ATM IV. Vol Sentiment: ilovevol.app cross-asset score (0 = stress, 100 = calm), one-year window unless noted.
This review is for informational and educational purposes only and is not investment advice. See the disclaimer.
The Daily Vol sends this review to your inbox each trading day: dealer gamma levels, the VIX curves, the SPX vol surface and the levels to watch. Free, one click to unsubscribe.