Home › Blog › Daily Market Review
Daily Market Review · US close
SPX sinks 3.7% to 6,910 as VIX jumps to 35.9 and VIX1D tops 51
A seventh straight loss put the S&P 500 in correction. SPX closed 552 points under its 7,462 gamma flip with net GEX at −$80.1B, VIX/VIX3M hit 1.160, the most inverted reading of the past year, and the surface prices a 2.3% move for Monday.
- The AI selloff turned into a rout: SPX −3.70% to 6,910, a seventh straight loss and an 8.6% weekly drop, NDX −5.61% and the Philadelphia chip index −10.7%, with Nvidia down 13.8%. The S&P 500 is now in correction and the Nasdaq Composite is negative for 2026.
- Net GEX is −$80.1B, a smaller number only because Friday's expiries rolled off. SPX closed 552 points under its 7,462 flip, with no positive strike within 6% of spot and the profile still near −$80B down to 6,500.
- Thursday's surface priced a 1.39% move and SPX moved 3.70%. VIX rose 7.45 to 35.89, its highest close of the past year, VIX1D 19.28 to 51.34, and VIX futures backwardation deepened to −7.77% M1→M2. The surface prices about 2.3% for Monday.
Scoreboard
| Close | Chg | Prev | |
|---|---|---|---|
| SPX | 6,910 | −3.70% | 7,176 |
| NDX | 25,029 | −5.61% | 26,517 |
| VIX | 35.89 | +7.45 | 28.44 |
| VIX1D | 51.34 | +19.28 | 32.06 |
| VVIX | 138.0 | +10.9 | 127.1 |
| VX Dec / Jan | 28.46 / 26.25 | −7.77% M1→M2 | −2.23% |
| VIX / VIX3M | 1.160 | +0.108 | 1.052 |
| 30D ATM IV / skew | 29.6% / 17.7 | +6.8 / +0.8 | 22.8% / 16.9 |
| Window | Net GEX | Chg | Prev | Flip | Call wall | Put wall | |
|---|---|---|---|---|---|---|---|
| SPX | All | −$80.1B | +$6.9B | −$87.0B | 7,462 | 7,000 | 6,000 |
| SPX | Weekly | −$16.6B | +$7.5B | −$24.1B | 7,474 | – | – |
| SPX | Monthly | −$51.6B | +$12.9B | −$64.4B | 7,508 | 7,000 | 6,500 |
| NDX | All | −$2.83B | −$0.00B | −$2.83B | 28,437 | 28,000 | 24,000 |
| NDX | Weekly | −$0.49B | −$0.05B | −$0.43B | 27,480 | – | – |
| NDX | Monthly | −$2.09B | +$0.21B | −$2.30B | 29,240 | 27,700 | 24,000 |
Dealer gamma by expiry window. All = every listed expiry; Weekly = contracts expiring within 7 calendar days; Monthly = within 30 days. Net GEX in $ per 1% move. From the site's stored end-of-day GEX history (Prev = its Nov 19 row); the stored history has no weekly walls.
1. The tape: chips crash, the S&P 500 enters correction
The S&P 500 fell 265.44 points (3.70%) to 6,910, a seventh straight decline and an 8.6% loss for the week, its worst since April 2025, per AP. It now sits more than 10% below its Oct 6 record, which puts it in correction. The Dow lost 949.73 points (1.93%) to 48,147, the Nasdaq Composite 5.28% to 22,618, erasing its gain for the year, the Nasdaq-100 5.6% and the Russell 2000 2.76% to 2,582. The damage was concentrated: AP noted most stocks outside technology rose.
Chips led the fall. The Philadelphia Semiconductor Index dropped 10.7%; Nvidia fell 13.8% for its ninth loss in ten sessions, and investingLive cited a Reuters report that the SEC is examining its accounting. AMD lost 13.3%, Micron 13.9% and Broadcom 12.1%, while AI infrastructure names such as CoreWeave (−12.1%), Bloom Energy (−15.3%) and Corning (−10.9%) went with them. Anthropic fell 9.1% to $88.30 on its second day, still above its $83 IPO price. General Mills (+3.7%) and staples were among the few gainers.
Rates offered some relief. The 10-year yield fell about 11 basis points to roughly 4.94% and the 2-year about 13 to 4.65%. Final University of Michigan sentiment rose to 51.5 from 48.0, with one-year inflation expectations down to 3.7%. Fed pricing did not move: Governor Cook said hikes are needed now, and CME FedWatch still put the odds of a quarter-point hike in December near 97%. Brent settled near $92.6, gold fell about 2.4% and bitcoin dropped below $60,000. Europe was weak too, with the DAX down 2.6%.
Why it matters for vol: Thursday's surface priced about a 1.39% move for Friday; SPX delivered 3.70% on monthly expiration day while dealers stayed deeply short gamma. The front end repriced violently: VIX1D above 50, VIX above 35, and the VIX futures curve in steep backwardation.
2. Dealer gamma: the book shrank, the hole did not
Net GEX across all expiries is −$80.1B per 1% move, from −$87.0B on Thursday's stored row. The improvement is the calendar, not repositioning: Friday's PM-settled expiry, which carried about −$14.9B on Thursday's live chain, rolled off. Net of that, the remaining book got roughly $8B more negative as SPX fell. The flip slipped to 7,462 from 7,501, and the index now closes 552 points (8.0%) below it, against 325 points on Thursday.
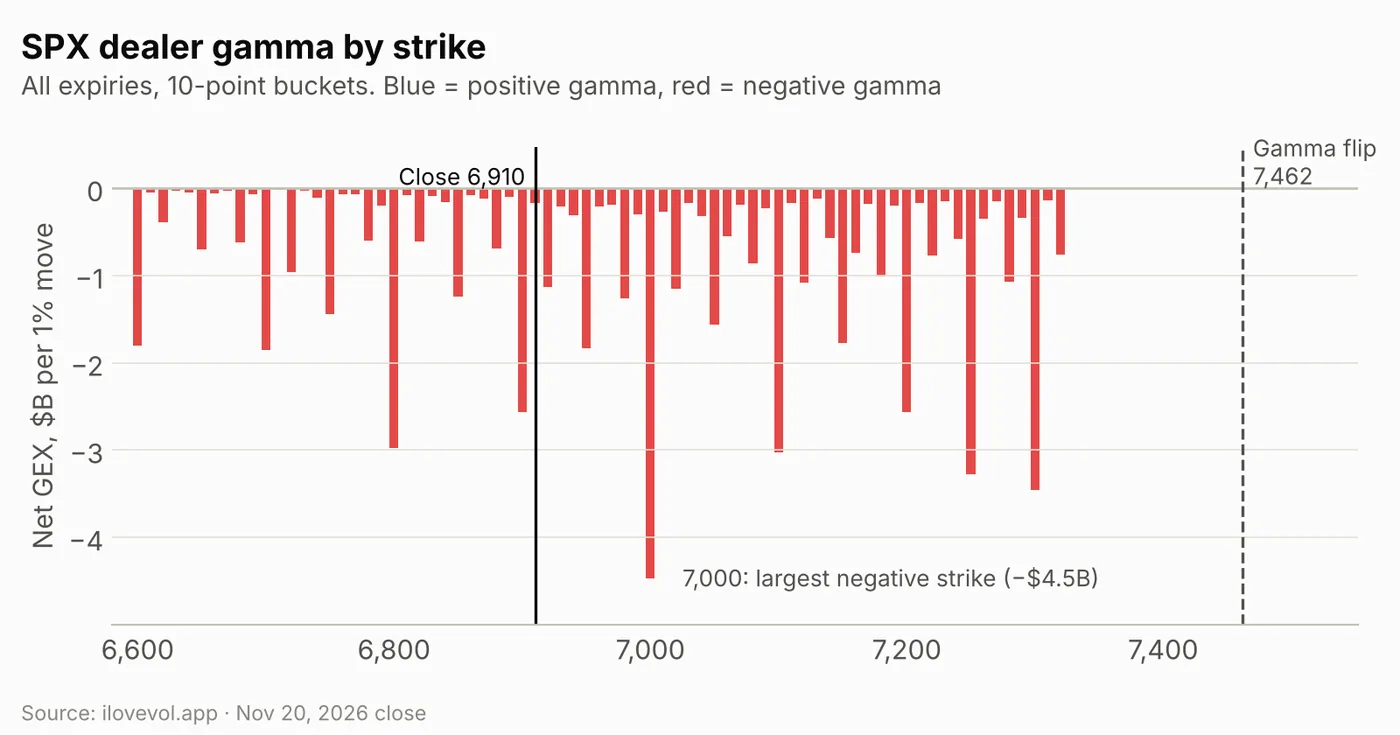
Every 10-point bucket within 6% of spot is negative; there is no positive strike in the range. The largest negative strikes are 7,000 (−$4.5B), 6,500 (−$4.1B), 7,300 (−$3.5B), 7,250 (−$3.3B), 7,100 (−$3.0B) and 6,800 (−$3.0B). The all-expiry call wall is now 7,000, just 90 points above the close, and the put wall 6,000.
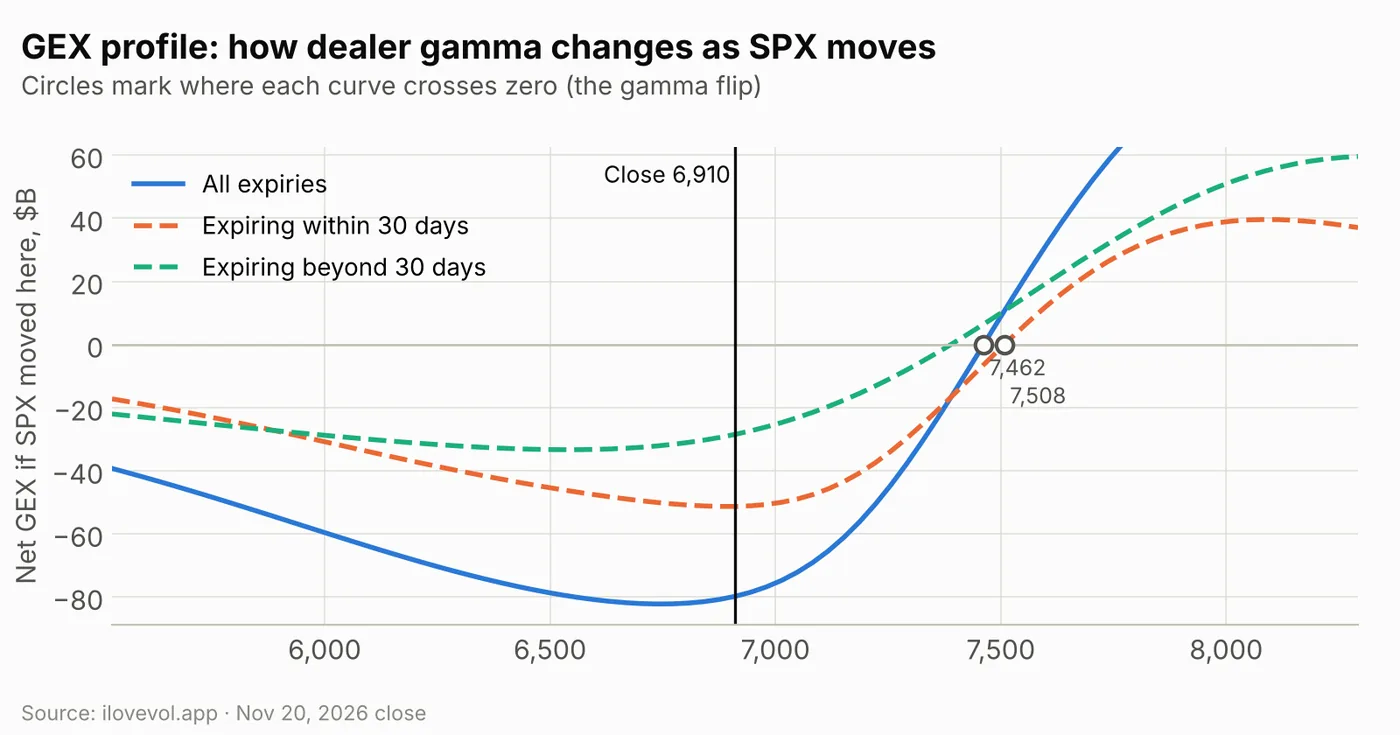
The modeled profile reads about −$80B at the close and bottoms near −$82B between 6,700 and 6,840. Above spot it eases only slowly at first: −$72B at 7,050, −$56B at 7,190 and −$31B at 7,330, before crossing zero near 7,460. Below spot it stays almost flat: −$81B at 6,840, −$79B at 6,500 and −$74B at 6,360. In other words, the short gamma does not fade on further declines; it would take a rebound of more than 300 points to cut it in half.
Expiries within 30 days hold about −$51.3B of the gamma at spot and those beyond 30 days about −$28.5B. The 30-day curve crosses zero at 7,508 and the beyond-30-day curve near 7,390, so the longer-dated book adds to the short gamma at this price rather than offsetting it.
Weekly vs monthly: every window is short
The three SPX flips sit within 46 points of each other, 552–598 points above the close: all-expiry 7,462, weekly 7,474 and monthly 7,508 (numbers in the dealer-gamma table under the scoreboard). The walls moved down with the index: the 30-day call wall fell to 7,000 from 7,700 and its put wall to 6,500 from 7,000.
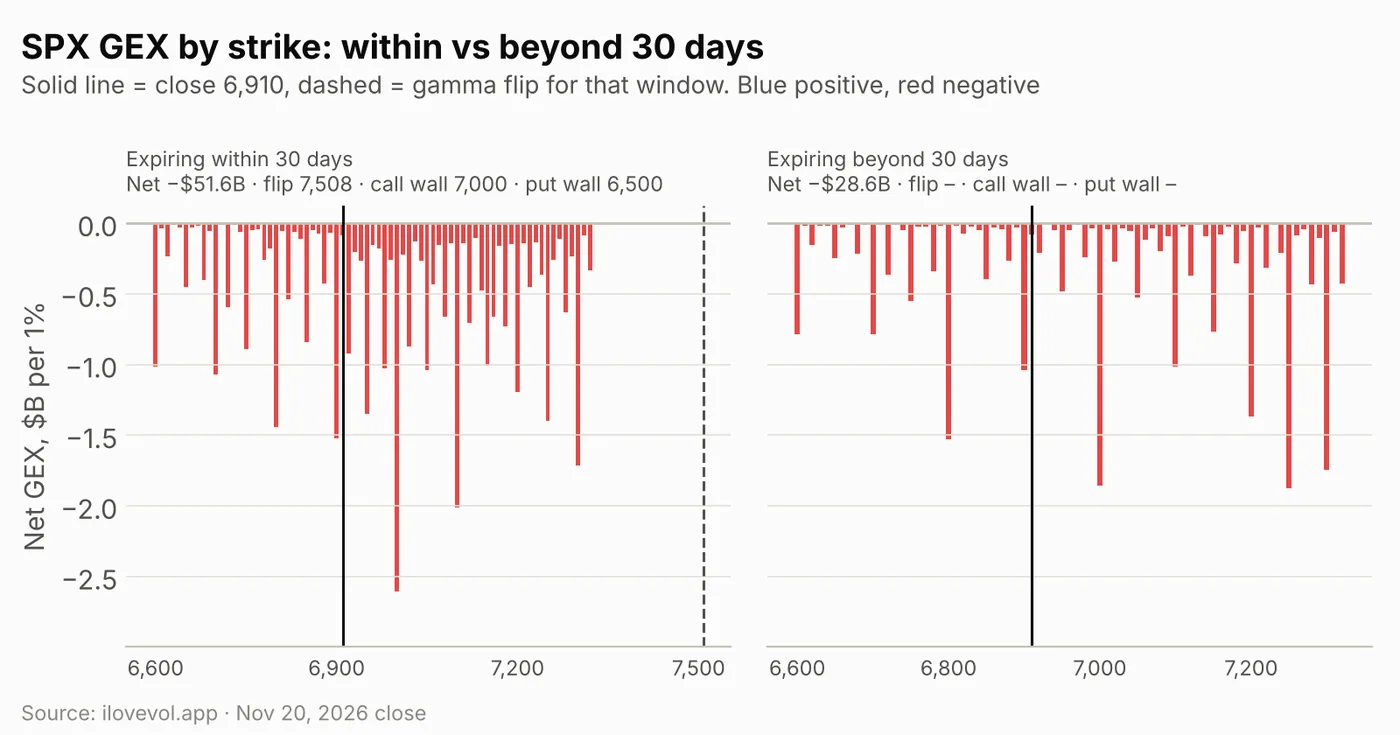
SPX weekly: the next 7 days hold −$16.6B, about 21% of the total, $7.5B less negative than Thursday because Friday's expiry is gone. The window covers a holiday-shortened week with PCE and GDP on Wednesday. The stored history has no weekly strike table, so the chart splits the book at 30 days instead.
SPX monthly: the 30-day window is −$51.6B (from −$64.4B), with flip 7,508, call wall 7,000 and put wall 6,500. Its largest buckets are 7,000 (−$2.6B), 7,100 (−$2.0B) and 7,300 (−$1.7B), with 6,800 and 6,900 near −$1.5B. Beyond 30 days the book is another −$28.6B, led by 7,250 (−$1.9B), 7,000 (−$1.9B), 7,300 (−$1.7B) and 6,800 (−$1.5B).
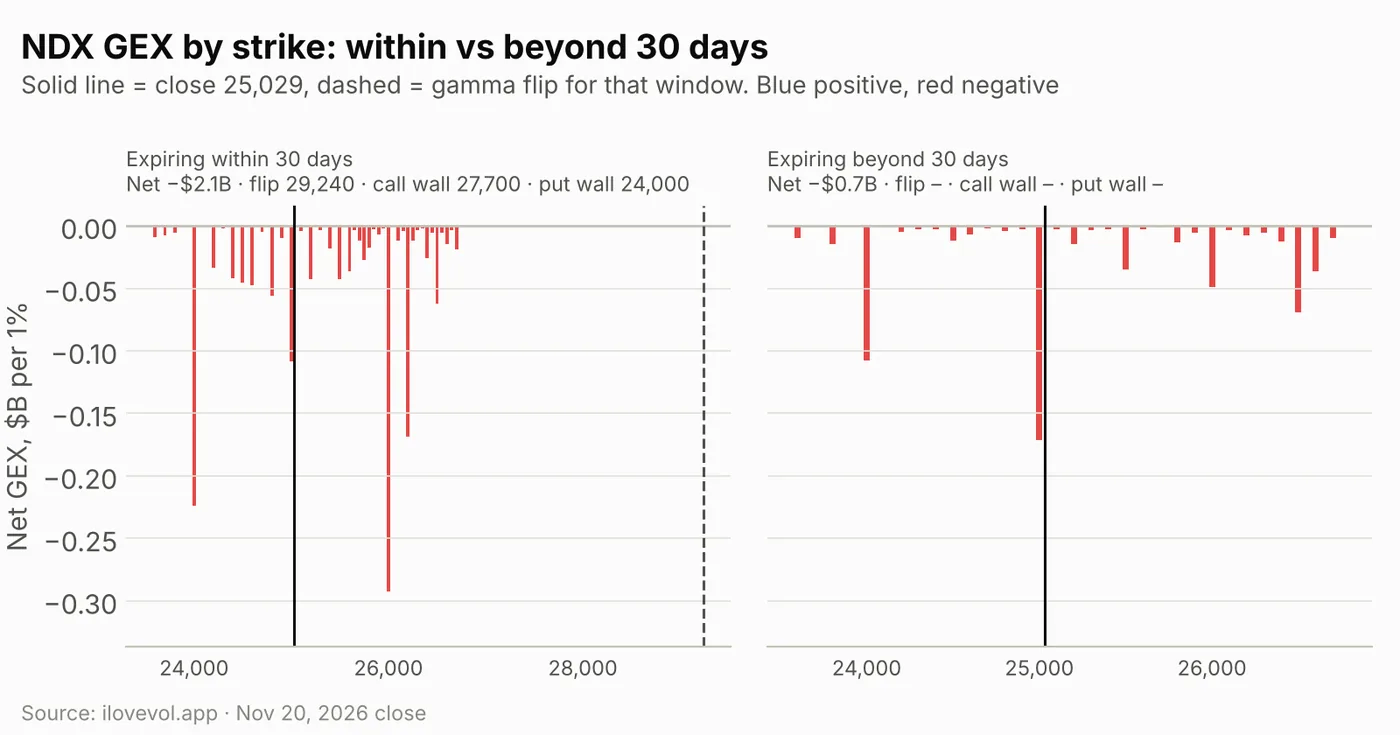
NDX fell 5.61% to 25,029 while its net GEX stayed at −$2.83B, as short-dated contracts rolled off and the remaining book grew more negative. It now sits 3,408 points under its 28,437 all-expiry flip, 2,451 under the weekly flip (27,480) and 4,211 under the monthly flip (29,240). The put wall dropped to 24,000, 1,029 points (4.1%) below the close; the 30-day window's biggest buckets are 26,000 (about −$0.29B) and 24,000 (about −$0.22B).
RUT fell 2.76% to 2,582, and its short gamma eased to −$2.61B from −$3.13B. It sits 347 points under its 2,929 flip, with the call wall at 2,700 and the put wall at 2,500.
3. The VIX complex: the steepest inversion of the year
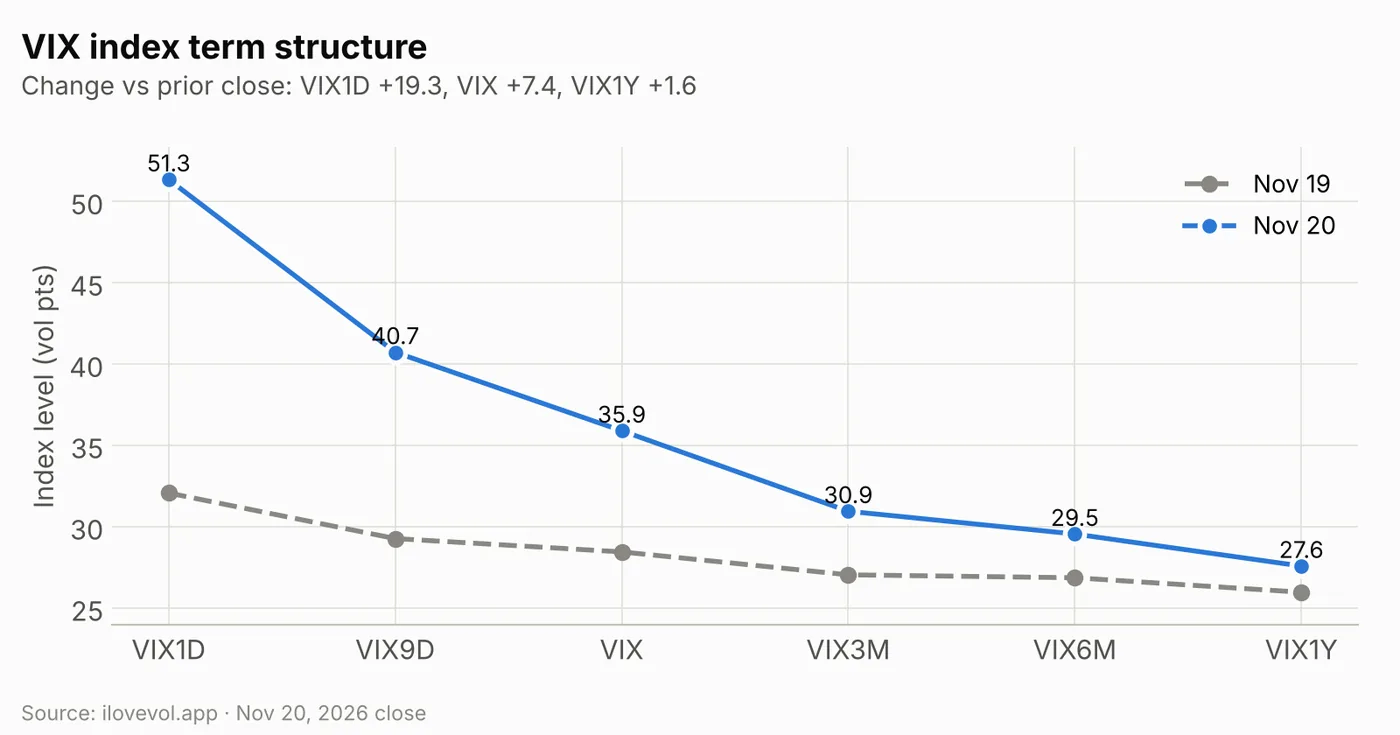
The index curve lifted and steepened downward. VIX1D jumped 19.28 to 51.34 and VIX9D 11.46 to 40.72, while VIX rose 7.45 to 35.89, VIX3M 3.91 to 30.94, VIX6M 2.69 to 29.54 and VIX1Y 1.61 to 27.57. VIX closed at its highest level of the past year, above every session in the window. VVIX rose 10.9 to 138.0, its highest since early March.
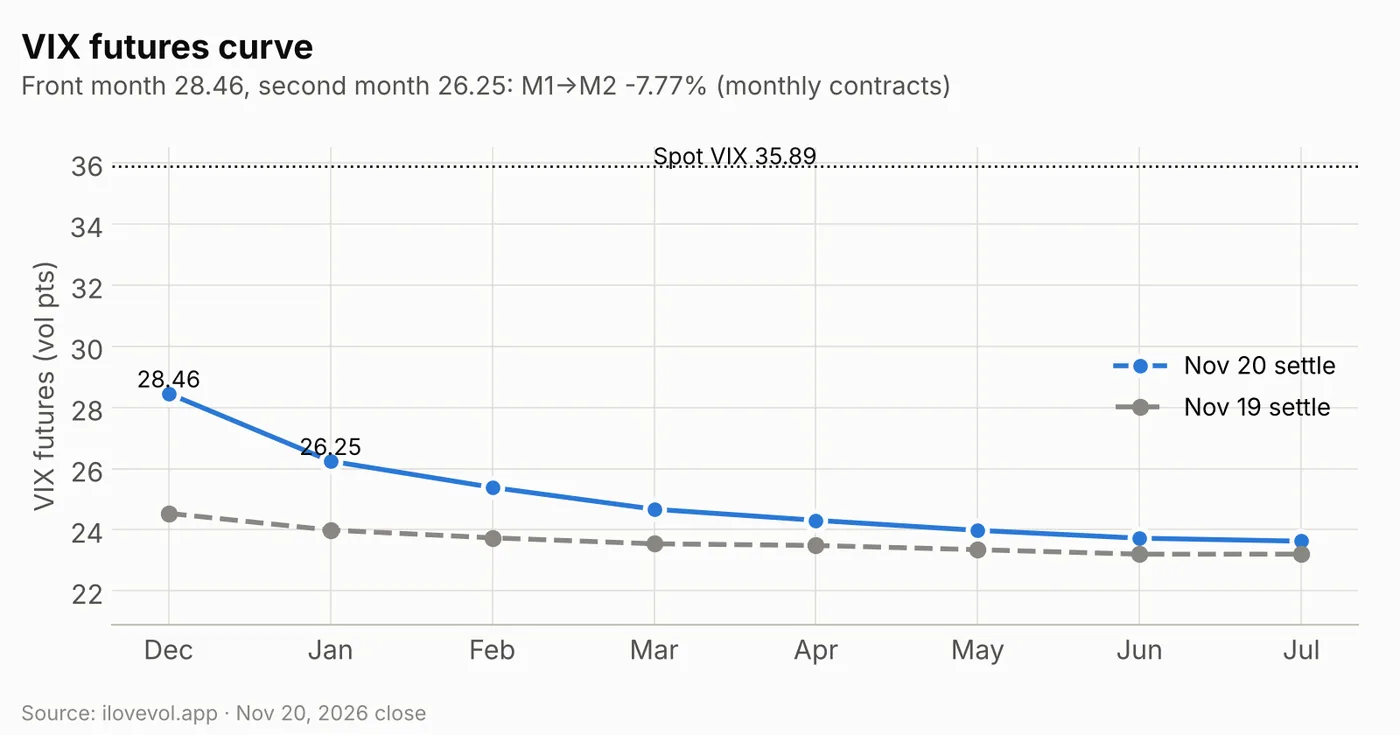
December VIX futures settled at 28.46, up 3.92, and January at 26.25, up 2.26, so M1→M2 deepened to −7.77% from −2.23%. The rise shrinks along the curve, from 3.9 points in December to about 0.4 in July. December still sits 7.43 points under spot, so futures price a substantial retreat from today's level by mid-December, even as they reprice higher.
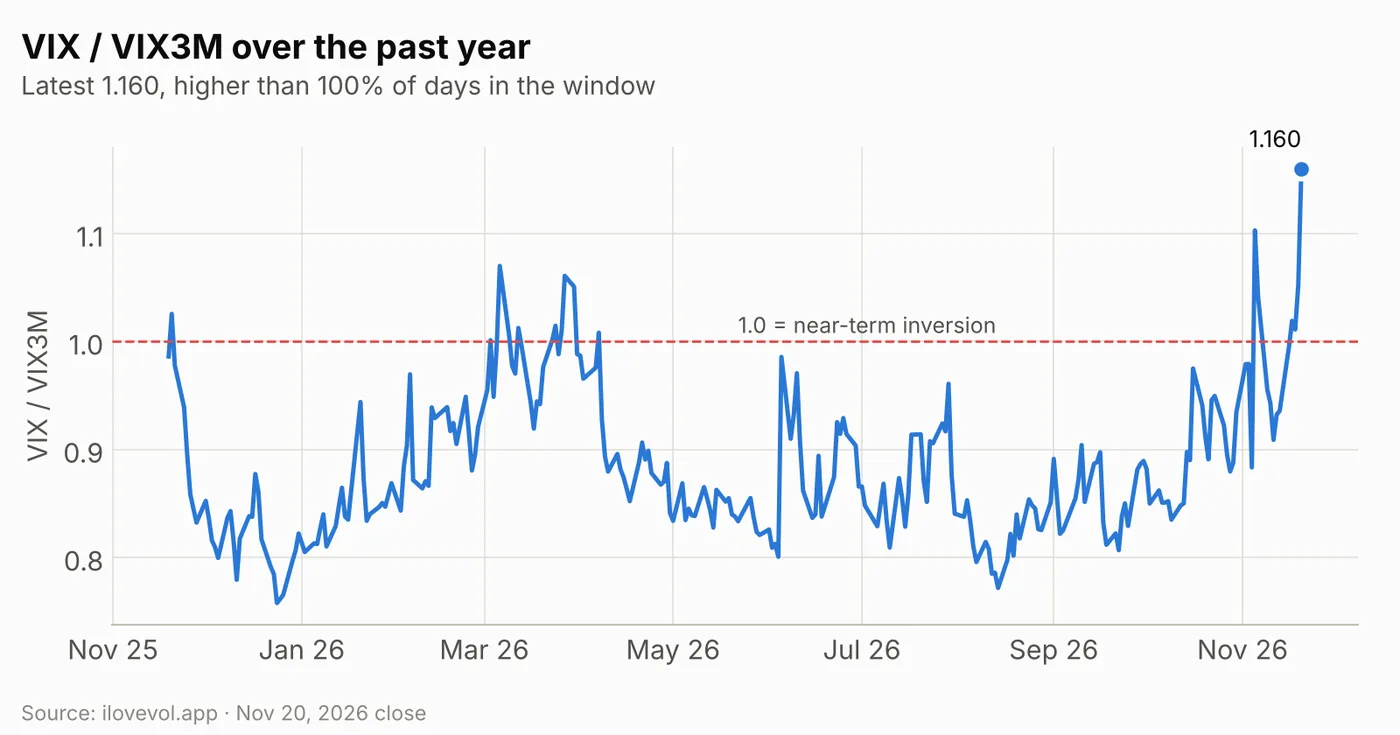
VIX/VIX3M rose to 1.160 from 1.052, the highest reading of the past year and well above the March and early-November spikes near 1.07–1.10. One-month implied vol is now priced about 16% above three-month.
4. Implied vs realized: both legs jump
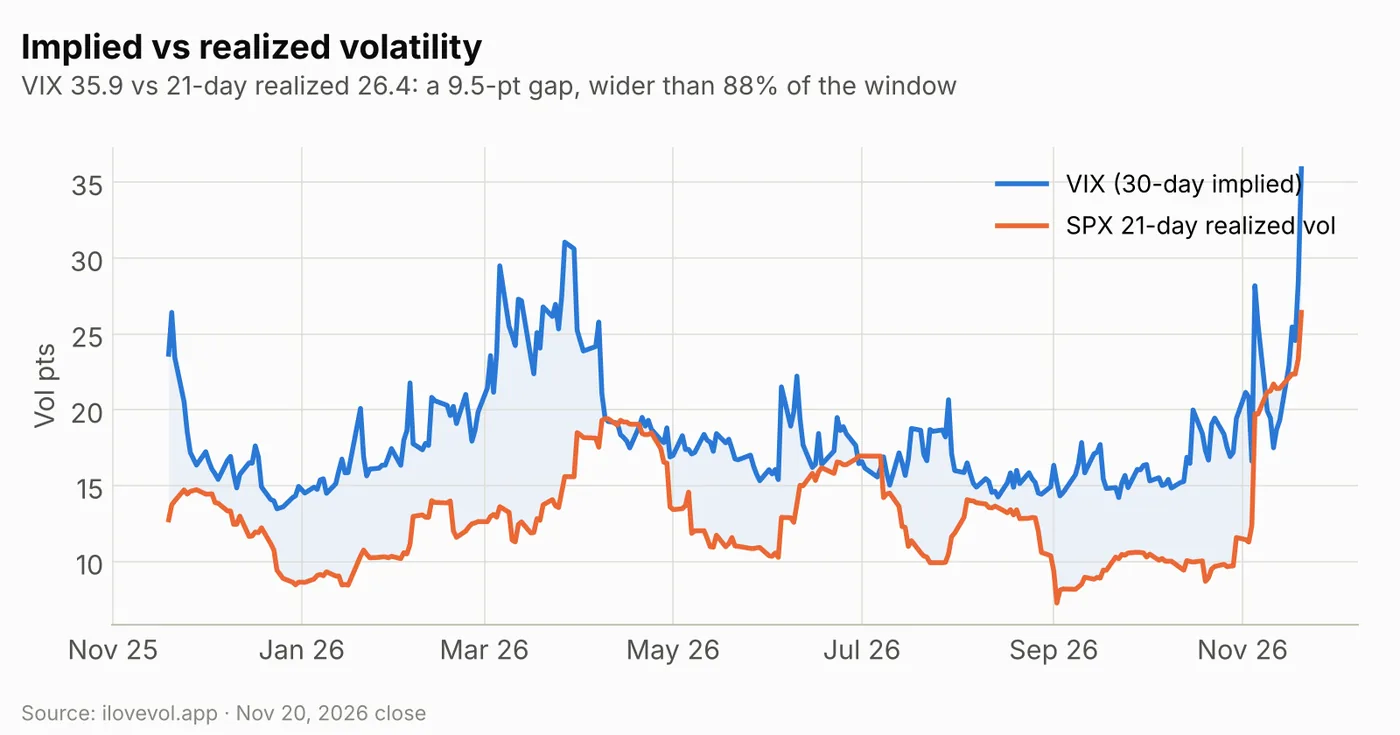
SPX 21-day realized vol rose to 26.4 from 23.4 after the 3.7% day, the highest in the window. VIX at 35.9 carries a +9.5-point premium over realized, up from +5.1 and wider than 88% of the past year. Thirty-day ATM IV on the stored surface (29.6%) is now 3.2 points above realized, after sitting below it on Thursday, so the premium is no longer only in the put wing.
5. SPX surface: the front end reprices, skew follows
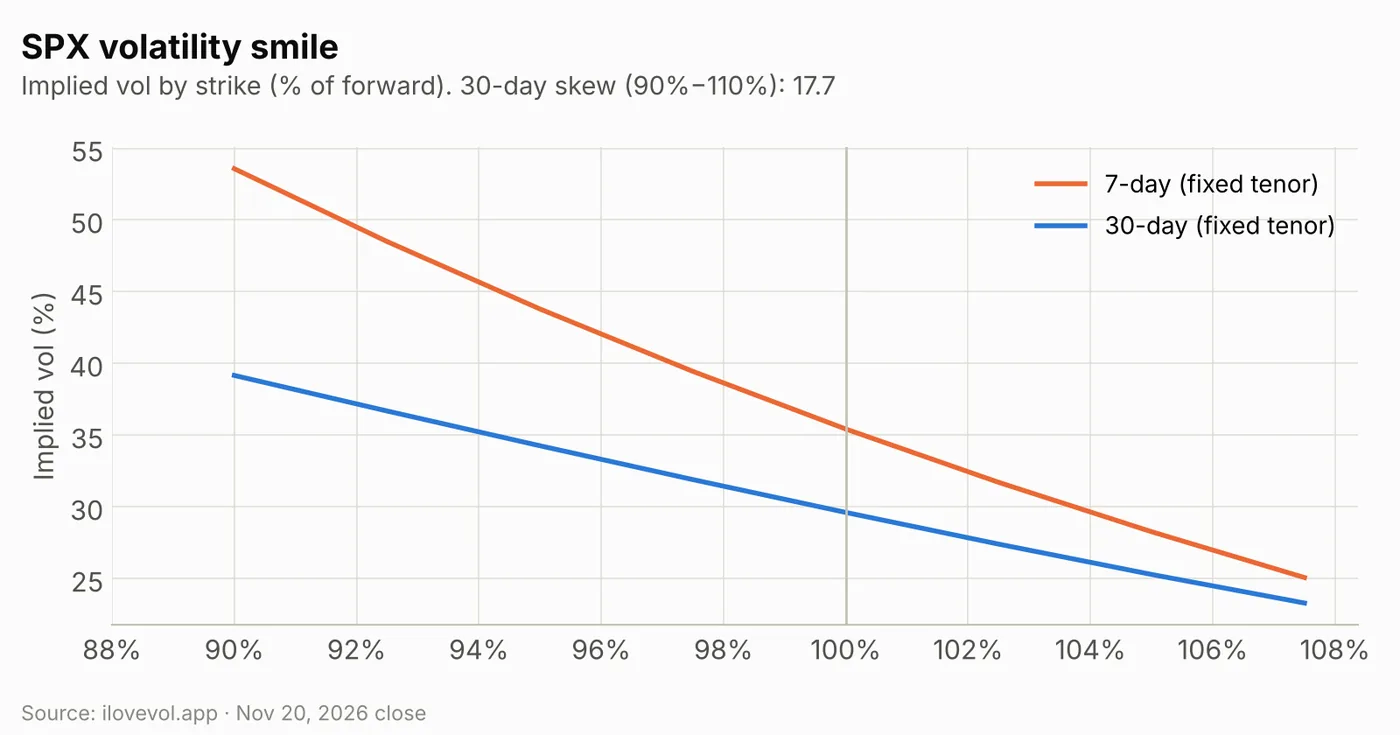
On the stored fixed-tenor surface, 30-day ATM IV jumped to 29.6% from 22.8%, and 30-day skew (90% vs 110% of the forward) steepened to 17.7 points from 16.9. The 25-delta risk reversal widened to 10.3 from 8.7. The term structure inverted further: 1-week ATM is 35.4% (from 25.5%), 1-month 29.6%, 3-month 24.1% and 1-year 21.3%, so the 1M–3M spread widened to 5.5 points from 2.3. The 7-day smile runs from about 54% at 90% of the forward to 35.4% at the money and about 25% at 108%.
The next-day move is priced at about 2.33% (roughly 161 points) for Monday, up from 1.39% on Thursday. Friday's 3.70% move was about 2.7 times what was priced.
6. Cross-asset Vol Sentiment: the stress spreads beyond US equities
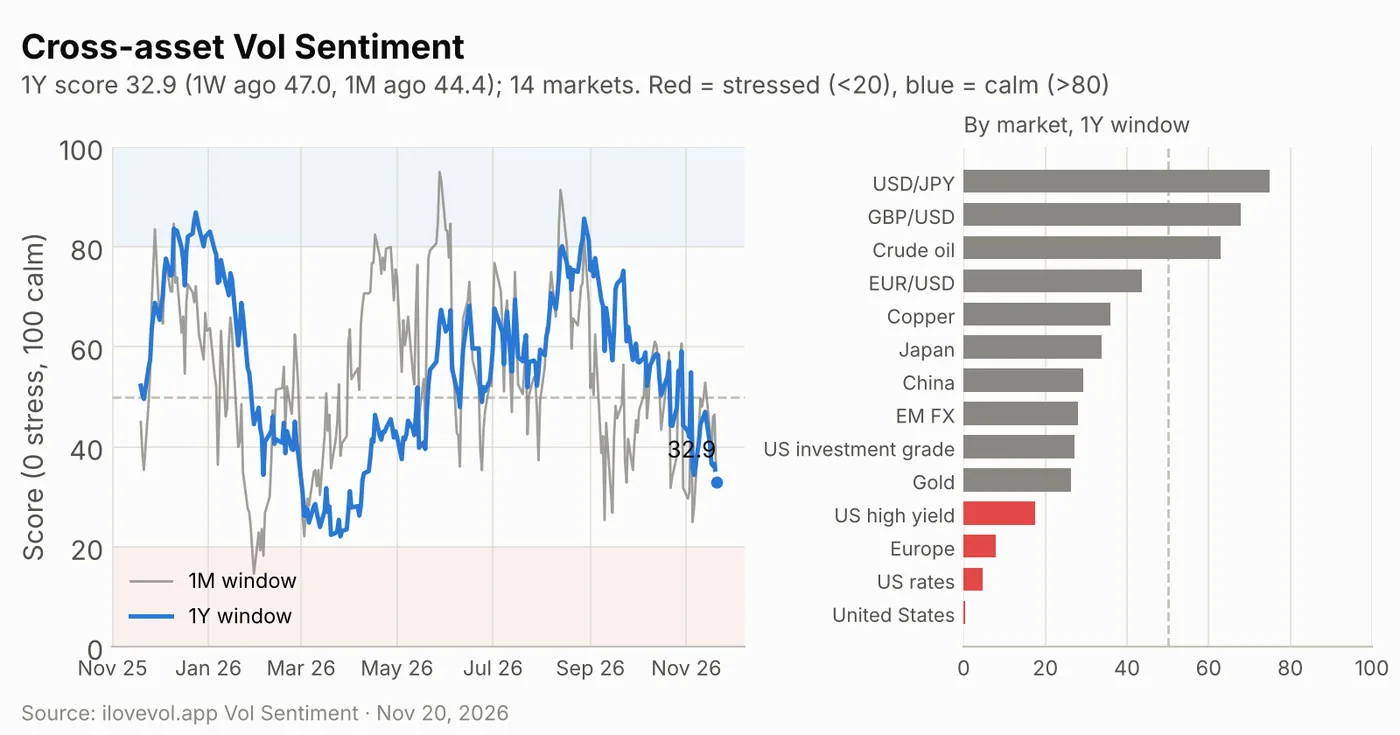
The cross-asset Vol Sentiment score places volatility in 14 equity, currency, rates, credit and commodity markets within its own one-year range (0 = stress, 100 = calm). On the one-year window it is 32.9, down from 36.6 on Thursday (revised), 47.0 a week ago and 44.4 a month ago, and higher than only 11% of the past year's sessions. The one-month score fell to 33.6 from 46.4, and the three-month score to 20.5.
Four markets are in the stressed zone below 20: US equities (0.4), US rates (4.6), Europe (7.9) and US high yield (17.5); no market is in the calm zone above 80. USD/JPY (75.0), GBP/USD (67.9) and crude oil (62.9) are the calmest. Unlike Thursday, the composite fell with US equities: Europe joined the stressed group and gold, copper and China all sit in the lower half of their ranges. The SPX surface already shows extreme stress; the cross-asset score adds that it is now broader than US assets. It is context, not a trading signal.
Calendar: the week ahead
Economic data & Fed
| Date | Time (ET) | Event | Note |
|---|---|---|---|
| Mon Nov 23 | 9:45 | S&P Global flash PMIs (Nov) | Monday move priced ~2.33% |
| Mon Nov 23 | 16:00 | Fed: Williams | ~97% odds of a December hike |
| Tue Nov 24 | 10:00 | Consumer confidence (Nov) | Case-Shiller home prices at 9:00 |
| Wed Nov 25 | 8:30 | Q3 GDP (second estimate), October PCE inflation, durable goods, jobless claims | Last data before the holiday; 1-week ATM 35.4% |
| Wed Nov 25 | 10:00 / 14:00 | New home sales (Oct); Beige Book | |
| Fri Nov 27 | 8:30 | Advance trade balance and inventories (Oct) | Early close |
Earnings
| Date | Timing | Companies | Note |
|---|---|---|---|
| Mon Nov 23 | After close | Zoom, Hewlett Packard Enterprise, Keysight (expected) | AI hardware read-through |
| Tue Nov 24 | Before open | Analog Devices, Medtronic, Best Buy | First chip report after the selloff |
| Tue Nov 24 | After close | Dell, HP Inc., Workday, Autodesk (expected) | AI server demand |
| Wed Nov 25 | Before open | Deere |
Volatility dates (expirations, events)
| Date | Event | Note |
|---|---|---|
| Thu Nov 26 / Fri Nov 27 | Thanksgiving / early close | Closed Thu; stocks close 1:00 pm Fri, eligible options 1:15 pm |
| Mon Nov 30 | Month-end SPX expiry | Inside the weekly window (−$16.6B) |
| Wed Dec 9 | FOMC decision | About 97% odds of a 25 bp hike priced |
| Wed Dec 16 | VIX December expiration | Dec future 28.46, 7.43 under spot |
| Fri Dec 18 | SPX December quarterly expiration | Within the 30-day window (−$51.6B) |
What I'm watching
- 7,000. The largest negative strike (−$4.5B) and now the call wall for both the all-expiry and 30-day books, 90 points above the close. Reclaiming it is the first sign of the hedging drag easing.
- 6,800, then 6,500. The next large negative strikes (−$3.0B and −$4.1B); 6,500 is also the 30-day put wall. The profile stays near −$80B through this whole range, so there is no gamma cushion below.
- 7,300 and 7,390–7,510. A large negative strike (−$3.5B), then the zone where the curves cross zero (beyond-30-day 7,390, all-expiry 7,462, weekly 7,474, monthly 7,508). Short gamma only fades meaningfully above 7,200.
- The 2.3% Monday move and VIX1D. VIX1D at 51.34 sits 15 points above VIX. A quiet Monday would let it collapse quickly; another day near Friday's 3.7% would confirm the front end was right.
- Backwardation. December VIX (28.46) is 2.21 above January and 7.43 under spot, with VIX/VIX3M at 1.160. Futures rising toward spot would mean the market no longer expects this level to fade by mid-December.
Sources
- NPR/AP: S&P 500 sinks 3.7% and the Nasdaq composite goes negative for the year
- investingLive: Americas FX news wrap 20 Nov: Stocks get hammered as Nasdaq plunges 5.28%
- Yahoo Finance: Chips are crashing like it's 2008 as the Nasdaq 100 nears a bear market
- Yahoo Finance: Stock market today: Nasdaq plunges, Dow and S&P 500 sink as Anthropic IPO fails to ease AI worries
- Yahoo Finance (Reuters): Wall St futures slip as Anthropic debut fails to reassure AI investors
- Kiplinger: What to Look Out for in Economic Data This Week (November 23-27)
- Admirals: Is the Stock Market Open on Thanksgiving and Black Friday 2026?
- Newsquawk: Week in Focus, November 23rd-27th
- IFYOUSPENT: Thanksgiving-week earnings: Dell, Workday, Zoom, HP, Deere
- TheStreet: Earnings Calendar, Week of Nov 23
Volatility data: ilovevol.app. This issue uses the site's stored end-of-day history (VIX history, GEX history, vol-surface history and Vol Sentiment) because the live feeds were unavailable after the close; GEX and surface changes compare the stored Nov 20 and Nov 19 rows. The Nov 20 PM-expiry figure (about −$14.9B) is from Thursday's live chain. GEX assumes dealers are long calls and short puts. VIX futures use settlement prices. Surface figures are fixed tenors (1 week, 1 month, ...); the next-day move is the surface's implied one-day move. Vol Sentiment: ilovevol.app cross-asset score (0 = stress, 100 = calm), one-year window unless noted; day-over-day changes use the latest (revised) prior row.
This review is for informational and educational purposes only and is not investment advice. See the disclaimer.
The Daily Vol sends this review to your inbox each trading day: dealer gamma levels, the VIX curves, the SPX vol surface and the levels to watch. Free, one click to unsubscribe.